Futures
Futures Settlement Explained: Cash vs Physical Delivery & Daily Mark-to-Market
Learn how futures settlement works: daily mark-to-market, cash settlement, physical delivery, final prices, expiry risk and practical ES, gold and oil examples.
On this page+
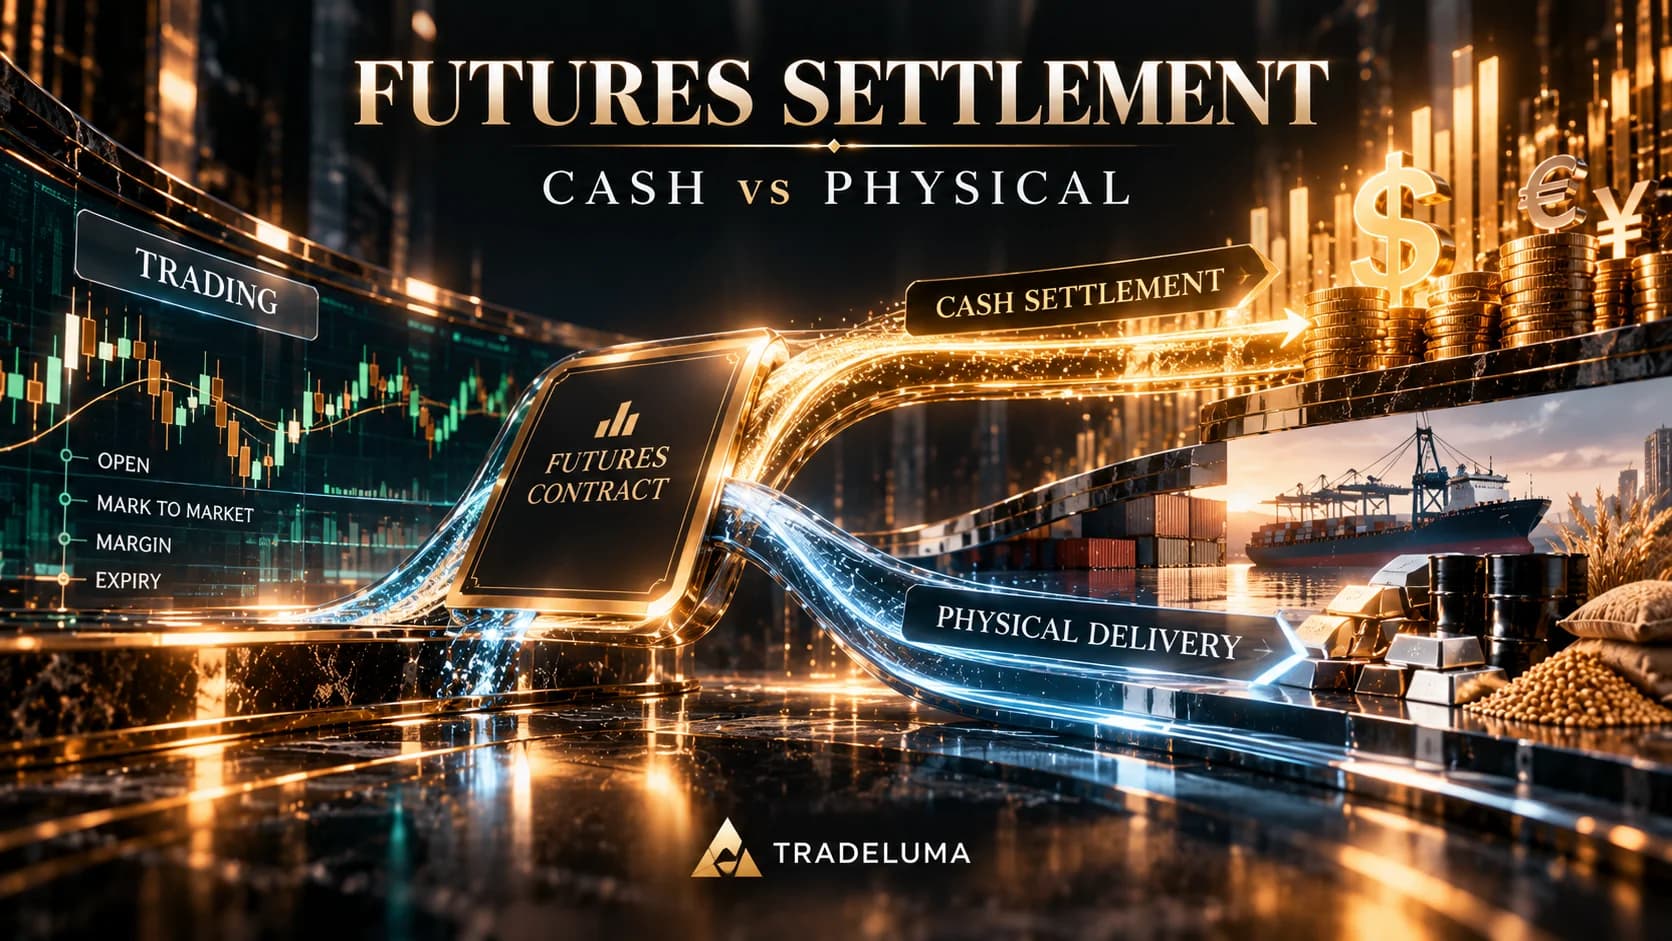
Every futures contract has a settlement process, but “settlement” can mean two very different events. During the life of a position, the clearing system uses a daily settlement price to mark open futures to market and transfer profits or losses. At the end of the contract, any position still open must follow its final settlement rules: some contracts settle in cash, while others can require making or taking delivery of the underlying commodity or financial instrument. This guide explains both meanings, compares cash settlement with physical delivery, and shows why expiry dates, broker rules and the actual tradable contract matter for manual and automated futures trading.
What is futures settlement? The two meanings traders need to know
Futures settlement is the mechanism for meeting the financial and, when applicable, delivery obligations of an exchange-cleared futures position. The word describes both the daily accounting cycle while a contract is open and the final settlement that happens when a contract reaches its maturity. Those two processes share a name but answer different operational questions.
Daily settlement asks how today’s price move changes cash balances and clearing requirements. Final settlement asks what happens to a contract that is still open at the end of its life: does the holder receive or pay a net cash amount, or must the long and short sides complete an approved delivery process? The answer is determined by the exact contract specification, not by how its chart looks.
Cash settlement vs physical delivery: the quick comparison
A cash-settled future is ultimately resolved at an exchange-defined final reference price. Remaining gains and losses are paid through clearing; no underlying physical goods need to change hands. Stock-index futures are common examples because an index itself cannot be loaded onto a truck. The final price can be based on a special opening quotation, a benchmark fixing or another rule defined by the exchange.
A physically delivered future specifies an approved deliverable asset and a delivery process. Qualified holders may be assigned to make or take delivery, subject to notices, quality standards, location, timing and clearing procedures. Gold, agricultural commodities and benchmark WTI crude oil demonstrate why delivery specifications matter. Not all contracts within an asset class share the same settlement method.
What daily mark-to-market means for a futures account
Cleared futures positions are normally revalued using the exchange’s official daily settlement prices. The resulting daily gain or loss is handled by the clearing system as settlement variation, often called variation margin. A rising futures price benefits a long position and hurts a short; a falling price does the opposite. Unlike a stock investment whose unrealised gain may simply remain on the screen, cleared futures exchange economic variation as part of the daily process.
This means a trader can owe money while still planning to hold the position and before final expiry. The daily cash accounting is distinct from the initial or maintenance performance bond that supports the open position. Broker interfaces differ in when they display and classify cash flows, so a platform’s “realised” or “unrealised” wording may not mirror the clearinghouse’s bookkeeping.
Worked MES example: two settlement days and a final result
Suppose one long Micro E-mini S&P 500 (MES) contract is bought at an illustrative 5,000.00. MES is worth $5 per index point. If the first official daily settlement is 5,008.00, the day’s trading variation is +8 points × $5 = +$40. If the next day settles at 4,996.00, the move from 5,008 to 4,996 is −12 points × $5 = −$60 for that day.
Across the two settlement moves, the accumulated result is −$20 before fees and slippage, equal to (4,996 − 5,000) × $5. The two daily cash adjustments do not create extra profit or loss; they allocate the same price change across days. For a short position, the signs reverse. A trader should still monitor available funds because interim losses can matter before any later recovery.
What determines the official daily settlement price?
An exchange publishes a settlement methodology for each product. It may use a volume-weighted average over a defined window, representative bids and offers, an approved price assessment or another contract-specific process. CME publishes daily settlement data and the underlying methodologies; there is no universal “4 p.m. close” calculation suitable for every futures market.
A chart’s final candle, a delayed quote, the last trade on the tape and the official settlement can therefore differ. That is not necessarily a data error. When reconciling overnight futures P&L, use the settlement price and trade-date conventions specified by the exchange and by the broker’s statements.
Variation margin vs initial and maintenance margin
Initial and maintenance margin are performance-bond requirements designed to support the clearing of a leveraged contract. Variation margin, in standard futures terminology, describes payments generated by changes in the marked-to-market value of open positions. One is collateral requirement; the other is cash flow linked to price movements. They interact, but they are not the same calculation.
If daily losses reduce account equity, a broker may request more funds, restrict trading or liquidate positions. Margin requirements can also change with market volatility and broker policy. The posted margin amount is never a reliable maximum-loss estimate: price risk depends on the contract multiplier, position size, market movement and execution conditions.
What happens when a cash-settled future expires?
At expiry, the exchange determines a final settlement price under the contract’s rulebook. The clearing system then calculates the final amount owed or receivable and extinguishes the remaining futures obligations. Because the reference is financial rather than a deliverable good, the holder does not receive physical stock-index baskets, barrels or metal merely by owning a cash-settled contract.
The final fixing may not equal the last traded futures quote. Some equity-index contracts rely on opening prices of underlying securities or special exchange calculations, while interest-rate and other financial products can use different reference formulas. Do not assume the usual daily settlement timestamp and the expiry fixing timestamp are identical.
Cash-settled examples: ES, MES, NQ and MNQ futures
E-mini S&P 500 (ES), Micro E-mini S&P 500 (MES), E-mini Nasdaq-100 (NQ) and Micro E-mini Nasdaq-100 (MNQ) equity-index futures are designed for financial settlement. Their multipliers differ by contract size, but they do not require taking ownership of all constituent shares as part of futures expiration.
A smaller multiplier changes the number of dollars per index point, not the fact that market exposure is leveraged. Contract rules, special fixing procedures and broker closeout policies still matter. Also avoid confusing the futures contract with options on that future: options can have their own exercise and settlement mechanics.
What happens when a physically delivered future expires?
Physically delivered contracts have a formal process for identifying which delivery obligations apply to eligible open long and short positions. The exchange and clearing members specify notice periods, tender or allocation procedures, delivery instruments or locations, quality grades and the payment arrangements. Delivery is a regulated contractual process, not a delivery truck turning up without documentation.
There can be several important dates before expiration, including first notice day, last trading day and broker-specific restrictions. The exact sequence varies by instrument and exchange. A participant who cannot or does not intend to complete delivery typically exits or rolls well before the applicable deadline, subject to the broker’s policy.
Gold futures delivery: GC and Micro Gold MGC
Benchmark COMEX Gold futures (GC) are physically deliverable and tied to exchange-approved gold delivery mechanisms. Micro Gold futures (MGC) are also physically deliverable, but their contract unit and operational delivery details differ. The existence of a Micro label should never be interpreted to mean a contract automatically settles in cash.
A retail broker may prohibit ordinary customers from entering or holding the delivery process and may close positions before exchange deadlines. Confirm the exact expiration month, first-notice requirements, permissions and the broker’s liquidation calendar. CME also lists other gold products with different cash-settlement specifications, so use the actual product code.
WTI crude oil: why physical delivery rules matter
NYMEX WTI crude oil futures (CL) use a physical delivery framework for eligible remaining positions. Its delivery conventions connect the exchange contract to the underlying crude-oil market. That does not mean every retail user of a CL chart is expected to take barrels: most speculative positions are closed or rolled before relevant delivery obligations arise.
The practical issue is that CL cannot be treated as interchangeable with every smaller or financially settled oil product. The product code, month, settlement type and broker eligibility determine what happens near expiration. The trader should never wait until the final trading session to discover that a broker has already imposed an earlier mandatory exit.
First notice day vs last trading day vs delivery day
First notice day typically marks when notices of intention to make delivery can begin for certain physically delivered contracts. Last trading day is the contractual endpoint for trading that expiry; delivery dates govern when transfer obligations are fulfilled. These dates do not necessarily occur in that order for every product, and some contracts have different notice conventions.
A safe contract calendar lists every relevant exchange date for the selected expiry as well as the broker’s internal closeout deadline. A common mistake is to watch only the final expiry date in a charting app and ignore that the broker may bar new positions or forcibly liquidate earlier.
Can you avoid physical delivery by closing the trade?
Usually a trader can avoid entering the delivery process by closing a physically deliverable futures position before the applicable broker or exchange cutoff. Rolling is another operational choice: close the expiring position and establish a position in a later month. The new position is a separate contract with its own price, liquidity, margin and expiration schedule.
The key is timing and execution. A broker might restrict trading or force liquidation when delivery risk approaches, and a crowded roll period can bring spreads and slippage. Closing “before expiry” is not precise enough if the relevant product permits delivery notices while trading is still open.
Final settlement price vs the last traded futures price
An exchange may determine the final settlement price using an official benchmark, a calculation based on underlying cash-market activity or another defined fixing window. The most recent futures trade is only one observation and need not be the price used to discharge final obligations. Thin trading near expiry makes this distinction especially important.
A platform may also display a continuous futures series that has been adjusted across contract rolls; that series is not itself the exchange-listed contract that will settle. Always reconcile the actual broker contract month and identifier when examining an apparently surprising final credit, debit or closeout.
The delivery method does not predict volatility or profitability
A cash-settled product is not inherently safer as a leveraged trade merely because its final obligation is financial. Both cash- and physically settled futures can move rapidly, experience gaps, become illiquid near expiry or trigger margin-related liquidation. Settlement method explains what remains to be done at expiry, not whether a trader will profit.
Likewise, a physically delivered futures contract is not automatically unsuitable for research, hedging or short-term speculation. It simply requires the correct operating procedures and sufficient knowledge of the contract terms, particularly when positions approach their notice or delivery periods.
Why expiry and settlement can distort backtests
Backtests built on continuous futures may blend several delivery months into one chart. Roll adjustments, last-price discontinuities and contract-specific trading volumes can change apparent returns even when the strategy code stays the same. Settlement data also have official publication times that can differ from trade data, so the backtest must avoid using prices before they were known.
An accurate simulation records the signal instrument, the tradable expiry, the roll policy, the true fill price, cash variation, transaction costs and the broker’s cutoff rules. A price series that looks beautifully continuous can conceal the inconvenient reality that one futures contract actually stopped trading and another began.
Settling trades versus settling contracts: a common mix-up
A filled futures order opens, reduces or closes a position in a particular expiry. That trade-level execution is different from a clearing cycle in which daily variation is posted, and different again from final contractual settlement. Some platforms use the word “settled” as a broad account statement label, which can blur these distinctions.
For an audit, keep timestamps and identifiers separate: exchange trade date, order fill time, contract month, daily settlement mark, realised trading cash flow, and final settlement or delivery event. Mixing those fields can create false P&L discrepancies even when every cash flow is correct.
What happens if the futures market moves sharply after settlement?
The daily settlement mark is a clearing reference point, not a promise that the market will stay at that price. Futures commonly continue to trade in extended sessions, and broker dashboards may update unrealised exposure using more recent quotes. The next clearing period captures additional market movements and cash obligations under its rules.
This matters especially around economic data, weekend gaps and overnight events. A trader whose account barely meets margin after one settlement may face a materially different risk profile before the next morning. A robust system monitors exposure and available liquidity throughout the trading session, not only after a daily statement is generated.
How brokers handle final settlement and delivery restrictions
Brokers often impose restrictions based on their operational ability to finance, document or process delivery. Policies may prohibit certain delivery-eligible positions outright, require earlier closeout than the exchange, raise margin requirements or liquidate remaining holdings without waiting for a customer instruction. The precise policies and fees vary by broker and product.
Therefore an exchange contract specification is necessary but not sufficient for a trading plan. The account holder should confirm broker permissions, product eligibility, position cutoffs, market-data access and the treatment of open orders and protective stops during forced closeout or contract expiry.
Automated trading: settlement-safe contract mapping
An automated futures system must distinguish a continuous chart signal from a verified tradable broker contract. Before submitting an order it should resolve contract code, expiry month, multiplier, tick size, settlement type, notice schedule, last trading day and the applicable broker-specific exit deadline. It should reject stale or ambiguous symbols rather than assume the front month from the chart is eligible.
Additional controls include disabling entries near delivery cutoffs, monitoring maintenance breaks, handling rollover explicitly, cancelling obsolete orders, reconciling broker fills with local positions and ensuring that paper and live modes use identical instrument metadata where possible. A contract that once traded normally can become unsuitable to open as it nears the end of its life.
Putting settlement into a complete futures trading plan
Settlement belongs alongside contract size, tick value, margin, liquidity and the trading calendar in the minimum specification check. Traders can reduce avoidable surprises by treating physical delivery as a contractual obligation to be understood before entering the trade, even when the intended holding period is short.
The essential distinction is simple: daily settlement is the ordinary mark-to-market accounting of an open futures contract; final settlement resolves the remaining contract at expiry through cash payment or the prescribed delivery mechanism. Once these processes are separated, broker statements, roll decisions and end-of-contract risk become much easier to interpret.
Frequently asked questions
What does settlement mean in futures trading?+
It can mean the daily official price used to mark open positions and transfer trading variation, or the final process used to discharge the contract at expiry through cash payment or delivery.
What is the difference between cash-settled and physically settled futures?+
Cash-settled futures close remaining obligations with a financial payment determined by an exchange-specified final price. Physically settled futures can require delivery of the underlying commodity or financial instrument under the contract rules.
Are futures marked to market every day?+
Cleared futures are generally marked to market through a daily settlement and variation process. That daily process occurs regardless of whether the contract ultimately cash-settles or delivers a physical asset.
Is daily mark-to-market the same as final settlement?+
No. Daily marking accounts for changes in open positions while the contract remains active. Final settlement resolves any remaining obligations when the contract reaches its maturity.
What is variation margin in futures?+
In standard futures clearing, variation margin refers to the cash amount exchanged because the position changed in value from one settlement point to another. It is distinct from initial or maintenance performance-bond requirements.
Can a futures settlement price differ from the closing price?+
Yes. Exchanges calculate settlement prices using defined windows or methodologies; the result can differ from the last displayed trade or a chart’s final candle.
Are MES and MNQ futures cash-settled?+
Yes. Micro E-mini S&P 500 (MES) and Micro E-mini Nasdaq-100 (MNQ) futures use financial settlement rather than delivery of their underlying stock-index constituents.
Are gold futures physically delivered?+
The benchmark COMEX Gold (GC) and Micro Gold (MGC) products are physically deliverable. Other gold-related products may have different settlement rules, so check the exact symbol and expiry.
Are WTI crude oil futures cash-settled?+
Benchmark NYMEX WTI crude oil futures (CL) use physical delivery. Other oil contracts can use different settlement arrangements; confirm the exact product code.
What happens if you hold cash-settled futures until expiry?+
The clearing system uses the final settlement price to calculate remaining cash obligations, and the futures contract expires without physical delivery.
What happens if you hold physically settled futures until expiry?+
If your position remains eligible for delivery under the product rules, you may have to make or take delivery. Many retail brokers restrict or liquidate such positions earlier.
What is first notice day in futures?+
It is a contract-specific date associated with the start of delivery notices in certain physically delivered futures. It can matter before the last trading day, and the precise rule varies by product.
Will my broker automatically close physically deliverable futures?+
Some brokers impose automatic closeouts or earlier cutoffs, but you should never assume that policy without checking your broker and the exact contract. Forced liquidation may bring fees and slippage.
Can futures losses exceed margin posted?+
Yes. Margin is collateral, not a limit on losses. Price gaps, fast markets and leveraged notional exposure can produce losses greater than posted margin.
Can a continuous futures chart itself be settled or delivered?+
No. A continuous series is a charting construct assembled from successive contract expiries. Settlement and delivery attach to a specific exchange-listed contract month.
How do trading bots avoid delivery and expiry mistakes?+
They should validate the broker contract ID and expiry, monitor first-notice/last-trade and broker deadlines, block entries near cutoffs, cancel stale orders and reconcile closing positions before rollover.
Futures workflows
Explore the strategy side of TradeLuma.
Browse TradeLuma's futures strategy catalogue and the chart, rollover, and reference methodology used for each published strategy.
Explore futures strategies →Continue learning
Related guides.
Futures Trading Hours: CME Globex, RTH, Overnight Sessions & Daily Breaks (2026 Guide)
Learn when futures markets open and close, including CME Globex hours for ES, MES, NQ, MNQ, Gold and Crude Oil, plus RTH, overnight sessions, breaks and time zones.
Open Interest vs Volume in Futures: How to Read Market Participation
Learn what futures open interest measures, how it differs from volume, what rising or falling OI means, and how rollover affects the data.
Contango vs Backwardation in Futures: Curves, Roll Yield & Examples
Understand contango and backwardation in futures, why curves slope up or down, how roll yield works, and what it means for oil, gold and rollover.