Futures
US Treasury Yields Explained: 2-Year vs 10-Year, Yield Curve Inversion & Market Impact
Understand US 2-year vs 10-year Treasury yields, yield curve inversion, real yields and the potential impact on gold, Nasdaq and Treasury futures.
On this page+
The 2-year and 10-year US Treasury yields are among the most watched signals in global markets. Their spread helps describe the shape of the yield curve; changes in nominal and real yields can influence gold, the US dollar, Treasury futures and Nasdaq valuations. But a curve inversion is not a guaranteed recession forecast, and an increase in the 10-year yield does not automatically mean stocks or gold must fall. This TradeLuma guide explains how the benchmarks are calculated, walks through basis-point and DV01 examples, and shows how traders can use the curve responsibly.
US Treasury yields explained: the short answer
A US Treasury yield is an annualised measure of the return implied by the market price and cash flows of a Treasury security. Two closely watched benchmarks are the 2-year yield, often sensitive to expected Federal Reserve policy, and the 10-year yield, reflecting expected future short rates alongside a changing term premium. Neither rate is the current Federal Funds target, and neither automatically determines the direction of gold or stocks.
The 2-year versus 10-year comparison is a compact way to discuss the yield curve: how interest rates differ with time to maturity. Traders track that relationship alongside inflation, jobs data, monetary policy expectations and liquidity. The most useful interpretation is not “higher yield equals sell” but what caused yields to change, which tenor moved, and what markets had already priced in.
What is a Treasury bond yield?
The US government borrows by issuing bills, notes and bonds with different maturities. Treasury notes generally pay a stated coupon every six months; the market price can rise or fall after issuance. The quoted yield to maturity is the discount rate that equates the present value of promised cash flows to the observed bond price, assuming payments occur as scheduled and the security is held to maturity.
A coupon rate belongs to the original security terms, but its yield changes with price. If a fixed-coupon note trades below par, its yield usually rises above the coupon rate. If it trades at a premium, yield usually falls below the coupon rate. Remember that the common “10-year Treasury yield” headline is normally a benchmark rate rather than the precise return earned by one investor.
Bond prices and yields move in opposite directions
A fixed-coupon bond pays the same dollar coupons regardless of what new issues offer. When prevailing market yields rise, existing lower-coupon bonds become less attractive unless their prices fall. When market yields fall, older coupons become more valuable and bond prices generally rise. This inverse price-yield relationship is central to Treasury futures risk.
The size of the price change is not uniform. Longer-duration securities typically have larger percentage price moves for the same yield change than shorter-duration securities, all else equal. Coupon, maturity, convexity and embedded contract-specific features matter. Do not infer that a 10-basis-point change in 2-year yields produces the same dollar P&L as a 10-basis-point move in 10-year yields.
2-year Treasury yield: what does it measure?
The 2-year Treasury yield is the annualised market yield at the two-year maturity point. Because much of its horizon lies close to the current and anticipated Federal Reserve policy path, it is often especially responsive to surprises in inflation, jobs data, Fed statements and interest-rate futures. That connection is important but not mechanical: the 2-year yield also contains risk and liquidity components.
Suppose a stronger-than-expected inflation release reduces the number of Fed cuts investors expect over the next two years. The 2-year yield might rise quickly as traders reprice that path. But if the report also signals a severe growth slowdown, risk aversion and long-horizon expectations could complicate the response. The net move reflects the full bundle of new information.
10-year Treasury yield: why is it watched?
The 10-year Treasury yield is an influential benchmark for longer-horizon borrowing costs and valuation assumptions. Its level reflects expected future short-term rates, inflation and real-rate expectations, and a term premium that compensates investors for holding longer-dated debt. Supply, demand, portfolio hedging and market functioning can all influence it.
Movements in the 10-year yield are widely discussed alongside mortgage rates, government financing costs, equity discount rates and gold. Those linkages are conditional, not fixed trading rules. A 10-year yield increase driven by stronger real growth may affect Nasdaq differently from an increase driven by inflation risk or Treasury supply concerns.
What are Treasury constant-maturity rates?
Many headlines and charts show 2-year and 10-year constant-maturity Treasury (CMT) yields. The US Treasury estimates a daily par yield curve from indicative quotations on recently auctioned securities, then reads benchmark rates at fixed maturity points. The resulting 10-year CMT value need not be the traded yield on an individual bond with exactly ten years remaining.
This difference matters when comparing chart websites, broker bond quotes and Treasury futures. A deliverable Treasury futures contract is driven by specific eligible securities and conversion factors, not by the CMT series itself. Use official Treasury data for benchmark yield-curve comparisons, and contract specifications for trading calculations.
What is the Treasury yield curve?
A yield curve plots yield on the vertical axis against maturity on the horizontal axis. A curve may slope upward, be approximately flat, or be inverted at selected maturities. In a normally upward-sloping curve, longer maturities yield more than shorter maturities; in an inverted portion, a shorter maturity yields more than a longer one.
There is no single mandatory slope measure. Analysts compare 10-year against 2-year yields (2s10s), 10-year against 3-month yields (3m10y), or multiple points along the curve. The curve can change shape even when the broad level of yields barely moves. Always specify the pair of maturities when discussing an inversion.
How to calculate the 10-year minus 2-year spread
The common 2s10s spread is: 10-year Treasury yield minus 2-year Treasury yield. Express the difference in percentage points, then multiply by 100 to obtain basis points (bp). One basis point equals 0.01 percentage points, or 0.0001 in decimal yield terms.
Illustrative example: if the 10-year yield is 4.40% and the 2-year yield is 4.00%, 4.40% minus 4.00% equals +0.40 percentage points, or +40 bp. If the 10-year yield is 4.10% and the 2-year yield is 4.75%, the same calculation gives -0.65 percentage points, or -65 bp. These are hypothetical numbers, not live market quotes.
Positive, flat and inverted curves compared
A positive 2s10s spread means the 10-year rate is higher than the 2-year rate. A spread around zero is a flat relationship between those two points. A negative spread is an inversion at the 2-year versus 10-year pair. None of these labels tells you whether Treasury prices rose or fell over the preceding trading session.
An inverted curve may reflect a restrictive near-term policy rate with expectations of future rate declines, but can also involve term premium and bond-market technicals. It is possible for a curve to re-steepen while yields rise, while yields fall, or while one maturity stays largely unchanged. The direction and reason for steepening matter.
Why does the yield curve invert?
A common mechanism is tight short-term monetary policy combined with expectations that future growth and inflation will cool. Short-maturity yields remain relatively elevated, while longer-term yields incorporate anticipated future cuts. Investors seeking duration, changing inflation compensation and shifts in term premium can also pull the 10-year yield below the 2-year yield.
Inversion is not proof that a recession is inevitable or that it will arrive on a fixed schedule. Curve signals may persist for many months and sometimes normalise without the commonly expected outcome. A trader should not use one threshold crossing as an exact entry trigger.
Does an inverted yield curve predict a recession?
Historically, certain Treasury-curve inversions have preceded US recessions, which is why the indicator draws attention. But the signal is probabilistic and vulnerable to false positives, changes in monetary-policy frameworks and the choice of maturities. An inversion does not tell you the precise start date, depth or probability of a recession without a model and a specified horizon.
An important detail: the Federal Reserve Bank of New York publishes a widely cited model using the 10-year minus 3-month Treasury spread, not the 10-year minus 2-year spread. The 2s10s inversion is a useful market shorthand, but it should not be misrepresented as the exact input to that NY Fed recession model.
10Y–3M versus 10Y–2Y: which curve matters?
The 3-month Treasury rate sits much closer to near-term policy and money-market conditions, making the 10Y–3M spread useful in some macroeconomic models. The 2-year yield embeds a longer path of expected policy and can move ahead of actual Fed decisions. As a result, 10Y–3M and 10Y–2Y can produce different readings on the same day.
For reliable research, use the same maturity definitions, timing conventions and historical data source throughout a backtest. A recession model calibrated on 3-month versus 10-year rates cannot simply substitute the 2-year rate and claim the same accuracy.
Bull steepening versus bear steepening
Steepening means the long-minus-short spread increases. In a bull steepener, yields generally fall and shorter yields decline more than longer yields; bond prices broadly rise. In a bear steepener, yields generally rise and longer yields increase more than shorter yields; bond prices broadly fall. These labels describe changes in rates, not whether a long equity trade would profit.
Example: 2-year yields fall from 4.20% to 3.90% while 10-year yields fall from 4.40% to 4.30%. The spread moves from +20 to +40 bp, a bull steepening. Alternatively, with the 2-year rising 10 bp and the 10-year rising 30 bp, the spread also steepens by 20 bp, but this is a bear steepening.
Bull flattening versus bear flattening
Flattening means the yield spread narrows. In a bull flattener, yields generally fall but longer yields fall more. In a bear flattener, yields generally rise but shorter yields rise more. These patterns may reflect different combinations of policy repricing, inflation compensation, growth expectations and demand for long-dated bonds.
Traders sometimes misread a narrowing spread as evidence that every yield is falling. In fact, 2-year yields could jump while the 10-year barely moves. Watch both series and the spread, rather than the slope chart alone, to identify the true driver.
Nominal yields versus real Treasury yields
A nominal Treasury yield reflects a dollar-denominated return before deducting inflation. A real yield is intended to capture the return after inflation adjustment. Treasury Inflation-Protected Securities (TIPS) provide market-based real yields, though TIPS pricing also reflects market liquidity and other technical factors.
At comparable maturities, nominal Treasury yield minus TIPS real yield is often called breakeven inflation. That difference is a measure of inflation compensation, not a pure forecast of future CPI or PCE: inflation-risk premium and market technicals can affect it. Track whether a nominal-yield move comes from real yields, inflation compensation or both.
Worked example: real yields and breakeven inflation
Hypothetical example: a 10-year nominal yield of 4.30% and a comparable 10-year TIPS real yield of 1.90% imply roughly 2.40 percentage points, or 240 bp, of breakeven inflation. If the nominal yield rises to 4.50% while the real yield rises to 2.20%, the breakeven falls to about 2.30%, even though the headline nominal yield increased.
The example shows why saying “higher yields mean higher expected inflation” can be misleading. Nominal yields may rise because real discount rates increased while inflation compensation fell. Index definitions, TIPS liquidity and observation timing matter when comparing the two.
Why gold often reacts to real yields
Gold does not pay a coupon. When the real return available on safe interest-bearing assets rises, the opportunity cost of holding a non-yielding asset may become more attractive, sometimes pressuring gold. Falling real yields can be supportive. This is one reason traders compare gold futures with real yields and the US dollar, not just the nominal 10-year yield.
Gold can still rise alongside higher real yields if geopolitical risk, official-sector demand, currency changes, liquidity stress or other forces dominate. A correlation is not a trading guarantee. The relationship also changes across time windows, so event-time price action and risk controls are essential.
How Treasury yields affect Nasdaq and stock-index futures
Higher longer-term discount rates can reduce the present value of distant expected corporate cash flows, a sensitivity often discussed for growth-heavy Nasdaq equities. But stronger yields can also accompany resilient earnings or accelerating growth. A yield jump during a strong jobs report may therefore create a different equity response than one caused by an inflation shock.
MES and MNQ futures are influenced by rates, earnings expectations, positioning, the dollar and market liquidity simultaneously. Avoid rules such as “10-year up means MNQ must fall.” Instead identify the source of the yield move, the timing of the economic release and whether the move changes policy or growth expectations relative to consensus.
Why the US dollar responds to yield differences
Treasury yields can affect demand for dollar assets, especially relative to bond yields in other economies. If US short-term yields reprice higher relative to comparable foreign rates, the interest-rate differential may help support the dollar. Currency movements also depend on global risk appetite, capital flows, hedging and central bank expectations.
For gold traders, the dollar and real yields can sometimes point in the same direction and sometimes conflict. Treat the cross-market picture as context. Dollar strength alone does not establish that an MGC sell signal is reliable.
Treasury futures: ZT and ZN are price-based contracts
CBOT 2-Year Treasury Note futures are commonly identified by the root ZT, while the benchmark 10-Year Treasury Note futures use ZN on many platforms. These traditional Treasury futures are quoted as prices. Broadly, higher Treasury yields imply lower underlying bond prices, but futures pricing also depends on the deliverable basket, conversion factors and cost of carry.
Do not trade a Treasury futures contract as though a one-basis-point move in the quoted CMT rate maps one-for-one to a fixed futures tick. Contract tick values, quotation conventions, expiry rules and cheapest-to-deliver characteristics differ. Verify the specific product and month with CME and your broker.
Duration and DV01: turning yield risk into dollars
DV01, or dollar value of a one-basis-point move, is an approximate dollar price sensitivity to a 0.01-percentage-point yield change. For a straightforward long bond position, a rise in yield usually produces a loss; a fall usually produces a gain. Duration translates yield changes into approximate percentage price changes, with convexity refining the estimate for larger moves.
For example, if a hypothetical long bond position has a DV01 of $70 per bp, a parallel 10-bp rise in the relevant yield implies roughly a $700 loss before convexity, financing and costs. This is not a published DV01 for ZT, ZN or any live contract: a real futures DV01 must reflect the product, current deliverable security and position size.
Yield futures versus Treasury-note futures
Besides traditional price-based Treasury futures, CME also lists certain yield-based futures designed to provide more direct exposure to Treasury yield changes. The contract mechanics and direction of gains can differ. Do not assume that a yield futures long position has the same directional exposure as a long Treasury-note price futures contract.
Broker symbols and eligible products vary. Always read the current contract specifications and check tick size, multiplier, expiry, settlement, margin and trading hours before placing orders. A strategy built for a price-based future should not silently route to a yield-based future.
Which events move the 2Y and 10Y most?
Key catalysts include CPI and PCE inflation, nonfarm payrolls, FOMC decisions, Fed speeches, Treasury auctions, debt-issuance announcements, growth data and unexpected liquidity events. Different releases can move the 2-year and 10-year maturities by unequal amounts. Strong inflation data may lift both; a growth scare may reduce expected policy rates and alter term premiums.
For event analysis, compare the actual release with a timestamped consensus forecast, not only the previous reading. Monitor revisions, core details and rate-futures pricing as well as the direction of the yield curve. Trading around major data releases carries widening spreads, slippage and rejection risk.
Example: a hot CPI print and the 2s10s spread
Imagine markets expected a monthly core inflation increase of 0.2%, but the released figure is 0.4%. Traders may reduce expected Fed cuts, pushing 2-year yields higher. If the 10-year increases by less, the 2s10s spread narrows, a bear flattening. If investors instead demand significantly higher long-term inflation compensation, the 10-year could rise more and the curve could bear-steepen.
Neither scenario is guaranteed. The reaction depends on detailed composition, initial positions, liquidity and central-bank context. Price actions in gold and MNQ should be checked against actual fills and exchange times rather than reconstructed from a later daily close.
Example: weaker jobs data and changing cut expectations
Suppose payroll employment undershoots consensus and wage growth cools. Markets might price earlier policy easing, causing the 2-year yield to fall faster than the 10-year and creating a bull steepening. But a deep growth scare may also drive powerful demand for longer Treasuries, flattening instead.
Compare the payroll surprise with unemployment, participation, wages and revisions. The jobs report draws from separate employer and household surveys, so a single headline does not fully describe labour-market conditions. An algorithm that keys off only the first payroll number is vulnerable to reversals when traders digest the details.
Using the curve for trend context rather than entry signals
The yield curve is best treated as macro context that helps interpret other markets. A trader might annotate sessions with the 2s10s spread, the direction of the 2-year and 10-year benchmark yields, the Fed policy-pricing change and the timing of key data. The resulting journal can reveal whether a strategy behaves differently in a steepening or flattening regime.
Do not assume any historical relationship will persist. Macro variables can be revised and calculated using different methodologies; markets respond to unexpected information, not just to the published level. Avoid adding a yield-curve filter to an automated strategy without robust out-of-sample testing.
How to read a Treasury yield chart without errors
Check the precise series name, observation time, maturity, units and chart frequency. US Treasury daily CMT rates are official model-derived par yields based on indicative quotes, not intraday executable prices. An intraday brokerage quote for an on-the-run 10-year note can differ from an end-of-day CMT reading for legitimate reasons.
When comparing two charts, use the same dates and units. A spread plotted in basis points may be labelled -35 rather than -0.35%; those are equivalent, but a mixed-units calculation can create a hundredfold error. Avoid mistaking a 30-bp yield move for a 30% change in yield.
Melbourne time zones and US economic releases
US data are commonly released in Eastern Time, but daylight-saving transitions in Australia and the US occur on different dates. A nominally fixed 8:30 a.m. US event will not always appear at the same Melbourne time across the year. Broker exchange clocks may also use Chicago time rather than New York time.
For automation, store the official event time in a timezone-aware calendar, convert for the actual date, and define pre-event, event and post-event behaviour. Do not hard-code the same Australian wall-clock hour for every release.
Risk controls for automated strategies during yield shocks
Before major macro releases, define the strategy’s maximum size, daily loss cap, price-deviation tolerance, pending-order cancellation policy and whether new entries are allowed during a release window. If yields and futures prices gap, ordinary stop orders can slip and stop-limit orders may fail to fill. A signal seen on a chart is not evidence of an executable trade.
An automated workflow should recognise rejected orders, stale quotes, partial fills and exchange interruptions. Use broker-position reconciliation after volatile events so a delayed close or duplicate alert cannot silently increase exposure. These operational controls matter regardless of whether a yield-curve thesis is directionally correct.
Backtesting yield-curve strategies without look-ahead bias
Use the data that would actually have been available at the tested timestamp. Daily Treasury curve figures published late in the US day cannot justify a trade placed earlier that morning. Historical curve values, survey expectations and news calendars require accurate release times, and revised series should not masquerade as contemporaneous observations.
Test costs, spread widening and event-time latency for MGC, MNQ or Treasury futures rather than relying on frictionless chart fills. Report performance by macro regime and validate on unseen periods. A visually compelling correlation between 10-year yields and gold can disappear after accounting for direction changes and realistic execution.
Quick checklist before trading on Treasury yield news
Confirm whether the headline is about the 2-year, 10-year or another maturity; whether the quote is intraday or an official end-of-day benchmark; and whether the move reflects real yields, inflation compensation or policy-rate expectations. Compute the 10Y minus 2Y spread with consistent units and inspect what changed compared with consensus expectations.
Then verify the broker symbol and futures contract, current liquidity, tick conventions, DV01 sensitivity and risk limits. A disciplined strategy treats the yield curve as one input to a broader process, not as a stand-alone instruction to buy gold, sell Nasdaq or predict recession.
Frequently asked questions
What is the difference between the 2-year and 10-year Treasury yield?+
The 2-year yield reflects a shorter horizon and is often more sensitive to expected Fed policy over the next few years. The 10-year yield reflects a longer horizon, term premiums and expected future interest rates. Both move with market pricing.
What does 2s10s mean?+
2s10s is shorthand for the 2-year versus 10-year Treasury yield comparison. The common 2s10s slope is 10-year yield minus 2-year yield, often expressed in basis points.
What is a basis point in Treasury yields?+
One basis point (bp) is 0.01 percentage points. A yield move from 4.00% to 4.25% is a 25-bp rise, not a 25% rise.
How do you calculate the 10Y minus 2Y spread?+
Subtract the 2-year yield from the 10-year yield. A 10-year yield of 4.40% and a 2-year yield of 4.00% give +0.40 percentage points, or +40 basis points.
What is an inverted yield curve?+
An inverted curve means a shorter maturity yields more than a longer maturity at the points compared. A negative 10-year minus 2-year spread indicates a 2s10s inversion.
Does an inverted Treasury yield curve guarantee a recession?+
No. Inversions have historically been associated with elevated recession risk, but are not a guarantee or a precise timing tool. The model, horizon and chosen maturities matter.
Does the New York Fed recession model use 2Y versus 10Y?+
No. Its widely cited recession-probability model uses the 10-year minus 3-month Treasury term spread. The 2s10s spread is a separate popular market indicator.
Why do bond prices fall when yields rise?+
Existing fixed coupons are less attractive when new bonds yield more, so their market prices generally decline to offer a competitive yield. The size of the move depends on duration and other factors.
Why does the 2-year yield move after a Fed announcement?+
Fed decisions and communication can change expectations for near-term policy rates. Those expectations are important for the 2-year yield, although term, liquidity and other market factors also contribute.
Why does the 10-year Treasury yield matter for Nasdaq?+
The 10-year yield influences long-term discount rates used in equity valuation. Higher rates can pressure growth-stock multiples, but earnings, growth expectations and investor positioning can override that effect.
Are higher Treasury yields always bearish for gold?+
No. Rising real yields and a stronger dollar can pressure non-yielding gold, but safe-haven demand, inflation concerns and central-bank purchases may dominate. The reaction is conditional.
What is the difference between nominal and real Treasury yields?+
Nominal yields are quoted before inflation adjustment; TIPS real yields reflect inflation-indexed Treasury pricing. Their difference at similar maturities is often called breakeven inflation, which also contains risk and liquidity effects.
What are bull steepening and bear steepening?+
Both mean the long-minus-short spread rises. Bull steepening usually occurs as yields fall faster at the short end; bear steepening usually occurs as longer yields rise faster.
What is DV01?+
DV01 estimates the dollar change in a bond or futures position for a one-basis-point move in yield. It depends on the instrument and position size, and is an approximation rather than a guaranteed P&L.
Are Treasury futures the same as Treasury yield futures?+
No. Traditional Treasury-note futures are price-based instruments affected by yields and deliverable bond mechanics. Certain yield futures have different contract conventions. Read the relevant exchange specification.
What are ZT and ZN futures?+
ZT and ZN are common CBOT symbols for 2-Year and 10-Year Treasury Note futures, respectively. Confirm the precise product, expiration, multiplier and order ticket with your broker.
Where can I check official US Treasury yields?+
The US Department of the Treasury publishes daily par yield curves and methodology. The Federal Reserve H.15 and FRED also provide widely used interest-rate series. Match the series and timestamp to your purpose.
Can I use the 2s10s curve as an automated trading signal?+
It can be researched as a contextual feature, but not assumed to be predictive. Use information available at decision time, out-of-sample testing, correct time zones and realistic trading costs and risk controls.
Futures workflows
Explore the strategy side of TradeLuma.
Browse TradeLuma's futures strategy catalogue and the chart, rollover, and reference methodology used for each published strategy.
Explore futures strategies →Continue learning
Related guides.
CPI vs PCE Inflation Explained: Why Gold, Nasdaq & Futures React
Learn how US CPI and PCE inflation differ, what headline and core readings reveal, and why surprises can move gold, Nasdaq and Treasury futures.
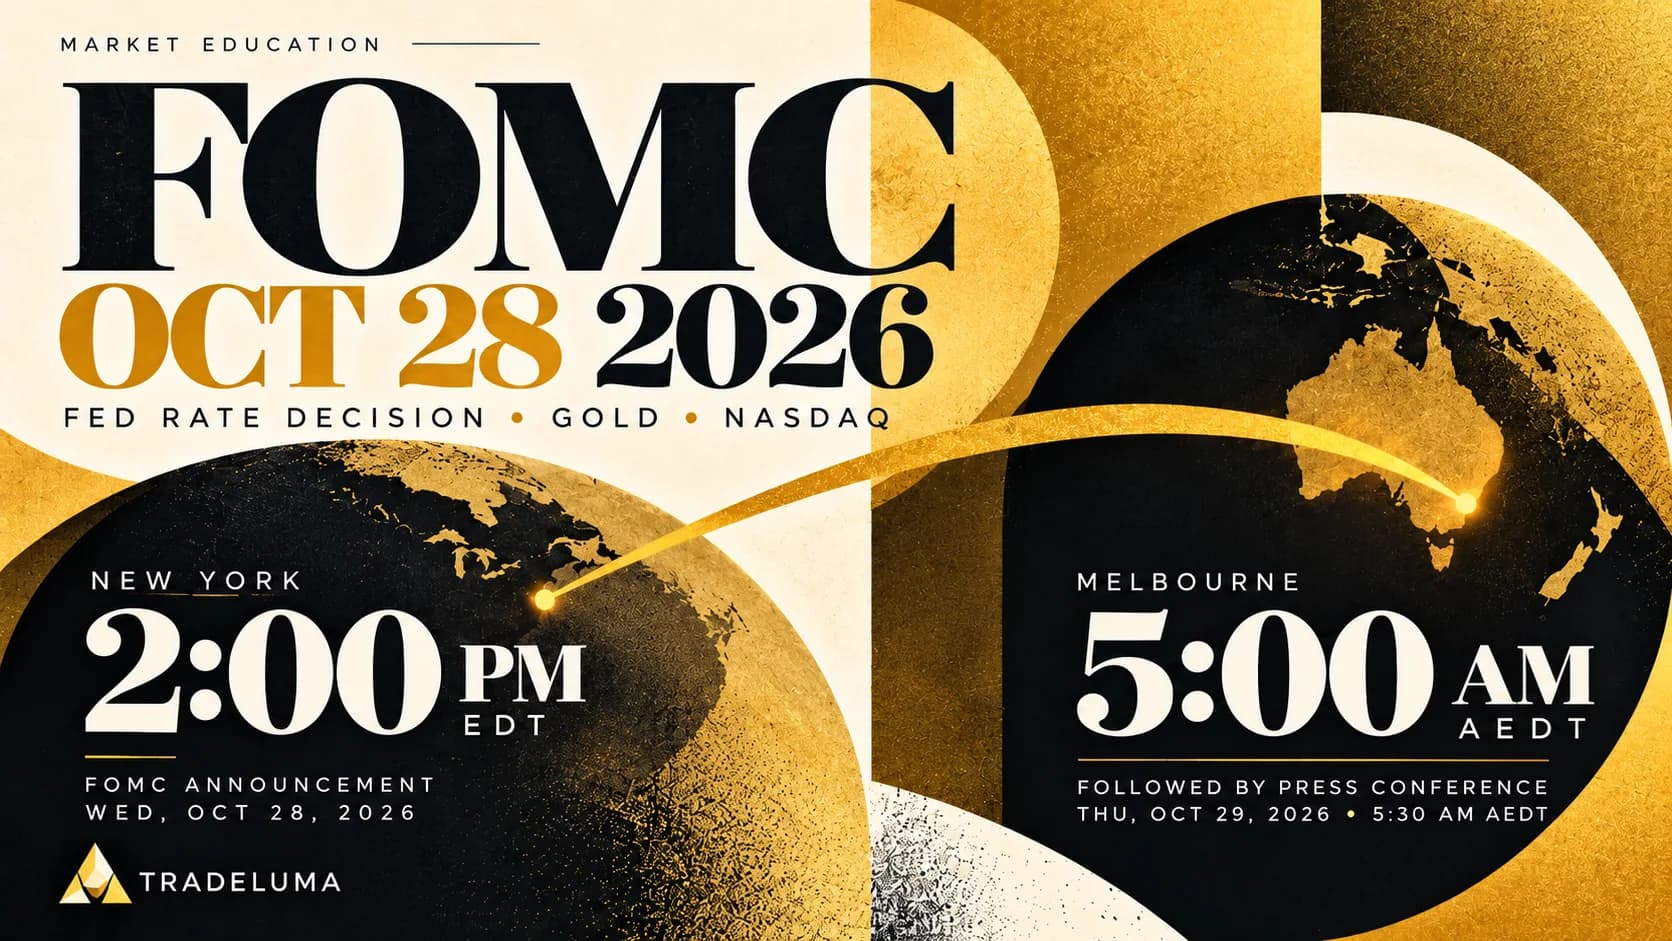
FOMC Meeting October 2026: Fed Rate Decision Time, Expectations & Gold/Nasdaq Impact
October 2026 FOMC decision time in New York and Australia, Fed rate expectations, statement and press conference explained, plus gold and Nasdaq trading risks.
Nonfarm Payrolls (NFP) Explained: Why Jobs Data Moves Gold & Nasdaq
Learn what US nonfarm payrolls, wages, unemployment and revisions mean, and why NFP surprises can move gold, Nasdaq and Treasury futures.