Futures
CPI vs PCE Inflation Explained: Why Gold, Nasdaq & Futures React
Learn how US CPI and PCE inflation differ, what headline and core readings reveal, and why surprises can move gold, Nasdaq and Treasury futures.
On this page+
CPI and PCE are the two US inflation measures traders watch most closely, but they do not measure precisely the same basket of spending. CPI can surprise markets before the later PCE release; PCE defines the Federal Reserve’s long-run 2% inflation target. Understanding the difference helps explain why the same inflation headline can move gold, Nasdaq futures, Treasury yields and expected interest rates in different ways. This TradeLuma research guide explains both measures, gives clearly hypothetical examples, and separates the economic signal from the risks of trading a volatile release.
CPI vs PCE: the short answer
The Consumer Price Index (CPI) and Personal Consumption Expenditures (PCE) price index both measure changes in US consumer prices, but they are not interchangeable. CPI comes from the Bureau of Labor Statistics (BLS); PCE comes from the Bureau of Economic Analysis (BEA). Their coverage, expenditure weights, source data and calculation methods differ.
The Federal Reserve defines its longer-run 2% inflation objective using the twelve-month change in the headline PCE price index. It also follows CPI, core PCE, wage data and other signals when judging inflation pressure. For traders, the useful question is often not which measure is “right,” but what a release changes about expected interest rates compared with the expectations already priced into markets.
What exactly is CPI?
CPI measures changes over time in prices paid by urban consumers for a market basket of goods and services. The commonly quoted headline is CPI-U, the Consumer Price Index for All Urban Consumers. The BLS releases headline, core and detailed category figures, typically showing both monthly and twelve-month changes.
CPI components include shelter, food, energy, medical care, transportation and many other consumer purchases. Items have different weights. A large move in gasoline prices does not have the same index effect as an equally large move in a higher-weight component, and a dramatic single component headline need not describe the whole basket.
What exactly is the PCE price index?
The PCE price index measures the prices of goods and services consumed by households as represented in the US national accounts. It has broader coverage than direct household out-of-pocket purchases and uses different spending data and aggregation methods from CPI.
An important example is health care: PCE includes certain expenditures made on behalf of households, such as some employer and government-provided medical services, whereas CPI focuses on qualifying out-of-pocket expenditures. That difference changes both coverage and relative weights.
Why the Fed targets PCE inflation
The Federal Open Market Committee (FOMC) states its longer-run inflation goal in terms of the PCE price index. The broader spending scope and ability of its formula to reflect changing consumption patterns are important reasons PCE is useful for policy analysis.
This does not make CPI irrelevant. CPI is timely, heavily watched, relevant to households and used in many indexation arrangements. The Fed assesses a range of inflation information, and neither a single CPI release nor one PCE observation mechanically determines the next interest-rate decision.
At a glance: CPI and PCE compared
Publisher: CPI is compiled by the BLS; PCE is compiled by the BEA. Reference population and scope: CPI represents purchases by urban consumers; PCE covers a broader national-accounts concept of household consumption. Primary price data: the two measures overlap in many places but use some different underlying sources.
Weighting and formula: CPI uses a modified Laspeyres-type approach at higher levels and household expenditure-based weights; PCE uses a chain-type Fisher-Ideal formula and national-account spending weights. Policy role: the Fed’s long-run 2% objective refers to PCE. Release timing: CPI and PCE arrive on separate scheduled dates.
The four reasons CPI and PCE diverge
The BEA groups differences into formula, weight, scope and other effects. Formula matters because PCE’s chain-type Fisher method adapts to changing spending patterns differently from CPI. Weight effects arise because the shares devoted to shelter, medical services, and other items differ.
Scope effects arise from expenditures included in one measure but not the other. “Other” includes differences in seasonal adjustment, source data and price concepts. A gap between CPI and PCE therefore need not be a data error, a contradiction, or evidence that inflation is being measured dishonestly.
Housing and shelter: a major weight difference
Housing-related prices, including owners’ equivalent rent in CPI, have a substantial influence on the CPI basket. PCE includes housing services too, but the relative share is generally lower because the PCE consumption base is broader.
Shelter is also a measured service concept rather than a live quote of house prices or mortgage repayments. Traders should not infer that a fall in property-sale prices immediately causes shelter CPI to fall, and should watch the publication definitions before interpreting an apparent lag.
Health-care spending and the scope effect
PCE’s treatment of health care includes payments made on consumers’ behalf, while CPI does not simply count all the same third-party expenditures. Different medical weights and price-source methods can help explain why headline or core readings separate.
The implication is analytical: if CPI medical services look unusually soft or strong, the effect on PCE inflation cannot always be estimated by applying CPI category weights directly.
Headline CPI, core CPI, headline PCE and core PCE
Headline measures include food and energy. “Core” conventionally removes food and energy to help analysts study underlying inflation trends without the most volatile categories. A core index is not the cost of living without essentials; it is a diagnostic measure alongside the broader headline number.
The Fed’s stated 2% longer-run target applies to headline PCE inflation, not an isolated month of core PCE. Policymakers often emphasize core PCE when evaluating persistent pressure because temporary gasoline or food shocks can obscure the underlying signal.
Month-over-month versus year-over-year inflation
Month-over-month (MoM) inflation compares an index with the previous month; year-over-year (YoY) compares it with the same month one year earlier. They answer different questions. A high YoY figure can coexist with a cooling recent monthly pace because old observations are still part of the twelve-month comparison.
For example, an illustrative sequence of 0.2% monthly increases would compound to about 2.43% over twelve months if repeated every month. That arithmetic is not a forecast. It also shows why a single 0.2% print should not casually be described as 2.4% annual inflation without explaining the assumption.
How to calculate an inflation rate from index levels
For any comparable index series, percentage change equals (new index / old index minus 1) multiplied by 100. If a hypothetical index rises from 300.0 to 300.9 over one month, its MoM change is 0.3%. For a YoY calculation, use the index for the same month of the prior year instead.
Use consistent adjustment conventions. A seasonally adjusted monthly comparison and a not-seasonally-adjusted twelve-month figure can be reported side by side; mixing the two without noticing can create false discrepancies.
How traders should read an inflation release
Read the release in a fixed order: confirm its reference month; identify the headline and core measures; distinguish MoM from YoY; compare actual results with a credible pre-release consensus; then inspect details and revisions. Finally, watch the market response and the path of policy-rate expectations.
The change versus consensus is usually more immediately relevant to a release-driven price reaction than whether the number is positive, negative or above 2% in isolation. Markets trade differences between new information and what was priced in beforehand.
Actual versus forecast matters more than the headline alone
Suppose core CPI is released at 0.3% MoM against an illustrative consensus of 0.2%. The positive surprise is 0.1 percentage point, even if 0.3% is below the previous month’s reading. The direction of the market response may depend on which details surprised, how positioning looked beforehand and whether other figures contradicted the headline.
A surprise is an observation minus an expectation; it is not the change from last month. Historical “hot” and “cool” labels become misleading when analysts forget the distinction.
Why CPI often moves markets before PCE is published
CPI is an important scheduled inflation release and may offer an early signal for parts of the later PCE reading, depending on the month’s release calendar and data sources. Markets may therefore adjust rate expectations after CPI even though the official Fed target uses PCE.
PCE is not a simple rescaled CPI print. The two measures use different components, weights and some separate source information, so a trader who simply copies CPI into a PCE forecast risks overlooking meaningful differences.
How hotter inflation can affect Fed rate expectations
When inflation is stronger than expected, traders may assign greater odds to policy staying restrictive for longer, all else equal. When readings undershoot expectations, the market may price a more accommodative path. The effect can be muted or reversed by growth, labor-market, financial-stability or policy-communication developments.
Watch the relevant rates market rather than guessing from the headline. CME FedWatch translates Fed Funds futures prices into model-implied FOMC outcome probabilities; these are market-pricing estimates, not official commitments by policymakers.
How inflation surprises can affect gold futures
Gold does not pay a coupon, so changing real yields and the US dollar are often useful channels for interpreting gold-price reactions. A hotter-than-expected reading that lifts inflation-adjusted yields or the dollar may pressure gold, other things equal.
But gold can rise on hot inflation if safe-haven demand, concern about policy credibility or other macro forces dominate. A “hot CPI means sell gold” rule is too simplistic for discretionary trading and is particularly fragile for automated systems reacting within seconds of release.
How CPI and PCE can move Nasdaq futures
Equity-index valuations are sensitive to discount-rate assumptions and expected earnings. A sharp upward repricing of expected policy rates may weigh on rate-sensitive growth shares and Nasdaq futures, while a benign inflation surprise can sometimes support them.
The direction is not guaranteed. If stronger inflation arrives alongside signs of resilient demand, or if investors already expected a worse number, the Nasdaq response may be different. Observe both the rates response and the earnings/growth interpretation before drawing conclusions from a single candle.
Treasury futures, yields and inflation surprises
Treasury bond prices and yields generally move in opposite directions. A release that pushes expected yields higher can pressure Treasury futures, although the size and maturity segment of the move matter. Short maturities tend to reflect the expected policy-rate path more directly than long maturities.
Distinguish nominal yields from real yields and expected inflation. A nominal-yield change may combine revised inflation expectations, policy expectations and term premiums. Never treat a one-point futures move as the same financial exposure across different Treasury contracts.
The role of the US dollar and cross-asset correlations
The dollar can strengthen when expected US rates rise relative to foreign rates, but relative monetary policy and risk appetite complicate the relationship. Dollar moves can influence dollar-denominated commodities and international assets, including gold.
Correlations are not stable laws. During stress, gold, the dollar and Treasuries can all attract defensive flows, or some can diverge. Risk management should not assume the normal inflation-day relationships will hold on every release.
Why a market can rise after a hot CPI or fall after a soft one
A release-day price change reflects the entire information set: consensus, positioning, revisions, components, market liquidity, central-bank credibility and subsequent commentary. Traders might also encounter an initial spike that reverses when the details are read.
A soft headline driven mainly by volatile energy can be less reassuring if core services accelerate. Conversely, a hot headline dominated by gasoline may be treated differently from a broad-based core surprise. The composition matters.
A practical CPI/PCE event checklist
Before the event, note the exact release time and time zone; identify consensus for headline and core MoM/YoY; mark the prior values and revision policy; confirm upcoming FOMC dates; check broker permissions, order-routing health and current positions.
During the event, monitor the release from an authoritative source and compare what was reported with what was expected. After the event, review changes in Fed Funds futures, Treasury yields, the dollar, gold and equity-index futures. Record the executed prices and slippage rather than comparing a strategy solely against the chart close.
Spread widening, slippage and stop orders at release time
High-impact news may coincide with a thinner order book, large spreads, rapid quote changes and partial fills. A stop-market order can execute much further away than its trigger; a stop-limit order can avoid some unfavorable prices but can also remain unfilled during a fast market.
Latency, stale quotes, rejected orders and position reconciliation can matter as much as whether a macro view was correct. For automated trading, test maximum daily loss, position caps, duplicate-alert protection and kill switches under realistic news-event conditions.
How to backtest CPI and PCE trading ideas responsibly
A valid event study requires timestamped releases, contemporaneous consensus forecasts, the exact contract being traded, realistic bid/ask and latency assumptions, commission, slippage and a method for handling revisions. Avoid retrospectively treating revised numbers as if traders knew them at the time.
Include no-trade sessions, unexpected holidays, contract rollover, out-of-sample periods and changes in volatility regimes. A model that works on a handful of spectacular inflation surprises can easily be an artifact of selection bias.
Common CPI versus PCE interpretation mistakes
Common errors include calling CPI the Fed’s official 2% target, describing core as more “true” than headline, mixing MoM and YoY, interpreting actual-minus-prior as a surprise, assuming PCE and CPI share identical weights, and treating a revised figure as original real-time data.
Other traps include relying on screenshots of outdated market-implied odds, presuming that higher inflation always moves gold and Nasdaq in fixed directions, ignoring the market’s forecast, and confusing a favorable forecast with a safe entry price.
CPI and PCE publication schedules and revisions
The BLS and BEA publish releases on their own calendars, typically at scheduled US Eastern times. Confirm the current official calendars rather than assuming a fixed day of each month, and account for US and Australian daylight-saving transitions before setting alerts.
PCE estimates may be revised as source data and national accounts are updated; some CPI data and seasonal factors can also be revised under published procedures. Use the data vintage appropriate to the task: latest available for current analysis, original release values for event-driven backtests.
How this topic connects to other TradeLuma research
Start with the CME FedWatch guide to understand how rate expectations are reflected in short-term interest-rate futures. Use the futures trading hours and trading fees guides to account for event timing and all-in execution costs, and the backtesting guide to avoid hindsight bias.
The core practical takeaway is to separate the economic data, what markets expected, how rates repriced, and how your actual order executed. Those are four different layers; blending them into one simple “CPI trade” is a common source of analytical error.
Final takeaway: interpret the difference, not just the number
CPI and PCE are complementary measures of inflation, not rivals where one makes the other irrelevant. The Fed uses headline PCE for its 2% target, studies underlying inflation through core measures and considers a broad set of economic evidence.
For a futures trader, disciplined analysis means reading the report definition and forecast first, checking rate expectations second, observing cross-asset reaction third and applying independent execution/risk controls throughout. No inflation statistic by itself is a reliable buy or sell signal.
Frequently asked questions
What is the main difference between CPI and PCE?+
CPI measures consumer prices for a basket based on urban household purchases; PCE measures prices for a broader national-accounts concept of household consumption. They differ in scope, weights and formulas.
Does the Fed target CPI or PCE?+
The Federal Reserve’s stated longer-run 2% inflation target is measured by the twelve-month change in headline PCE inflation.
What is core PCE inflation?+
Core PCE is the PCE price index excluding food and energy. Policymakers monitor it to assess underlying inflation trends, but the formal 2% target is for headline PCE.
Is core CPI the same as core PCE?+
No. Both omit food and energy, but they use different expenditure coverage, category weights, source data and index construction.
Why is CPI usually higher than PCE inflation?+
CPI has often measured somewhat higher inflation over long periods, partly because of formula and weight effects, but the difference is not fixed and can change sign in some months.
Does CPI include housing costs?+
Yes. Shelter is an important component of CPI, including rent and owners’ equivalent rent. It is not simply the same as a house-price index or mortgage repayments.
Why does health care matter more in PCE?+
PCE includes some medical spending made on households’ behalf, such as payments by employers or governments, while CPI focuses on qualifying consumer out-of-pocket spending.
What is the difference between headline and core inflation?+
Headline includes food and energy; core excludes them to help reveal underlying trends. Both matter and neither by itself describes every household’s expenses.
Is 0.2% monthly inflation equal to 2.4% annually?+
Not automatically. If 0.2% repeated for twelve months, compounding would produce roughly 2.43%. A single monthly reading is not a forecast for the remaining months.
What is an inflation surprise?+
An inflation surprise is the reported figure minus the market consensus forecast for the same measure and period, not necessarily the change from the prior month.
Why can gold fall after CPI?+
If CPI pushes the market to expect higher real yields or a stronger US dollar, gold may weaken. Other forces can dominate, so the response is not guaranteed.
Why can Nasdaq futures rise after a hot CPI?+
If the market anticipated an even hotter number, focuses on resilient growth, or reverses initial positioning, Nasdaq futures can rise despite a superficially hot report.
Does CPI predict the next PCE print?+
CPI provides useful inputs and clues for some PCE components, but separate weights, scope and source data mean the two releases cannot be treated as identical.
What time are US CPI and PCE released?+
Follow the official BLS and BEA release calendars for current schedules and US Eastern publication times. Convert carefully for daylight saving in your location.
What does FedWatch have to do with inflation?+
FedWatch uses Fed Funds futures to estimate probabilities of FOMC target-rate outcomes. Inflation surprises can shift those expectations, but FedWatch readings are market-implied estimates rather than Fed promises.
Is trading gold or MNQ during CPI safe with a stop-loss?+
A stop does not guarantee the execution price. Fast markets may have gaps, wide spreads and slippage. Position sizing and order controls remain essential.
Which number should I look at first on CPI day?+
Confirm the release reference month, headline and core month-over-month versus consensus, year-over-year context and category detail, then check rate-market repricing.
Can I backtest inflation releases using today’s historical data?+
Only with caution. Use original data vintages and historical consensus forecasts, not later revisions, and include live-realistic spreads, latency, slippage and execution constraints.
Futures workflows
Explore the strategy side of TradeLuma.
Browse TradeLuma's futures strategy catalogue and the chart, rollover, and reference methodology used for each published strategy.
Explore futures strategies →Continue learning
Related guides.
Nonfarm Payrolls (NFP) Explained: Why Jobs Data Moves Gold & Nasdaq
Learn what US nonfarm payrolls, wages, unemployment and revisions mean, and why NFP surprises can move gold, Nasdaq and Treasury futures.
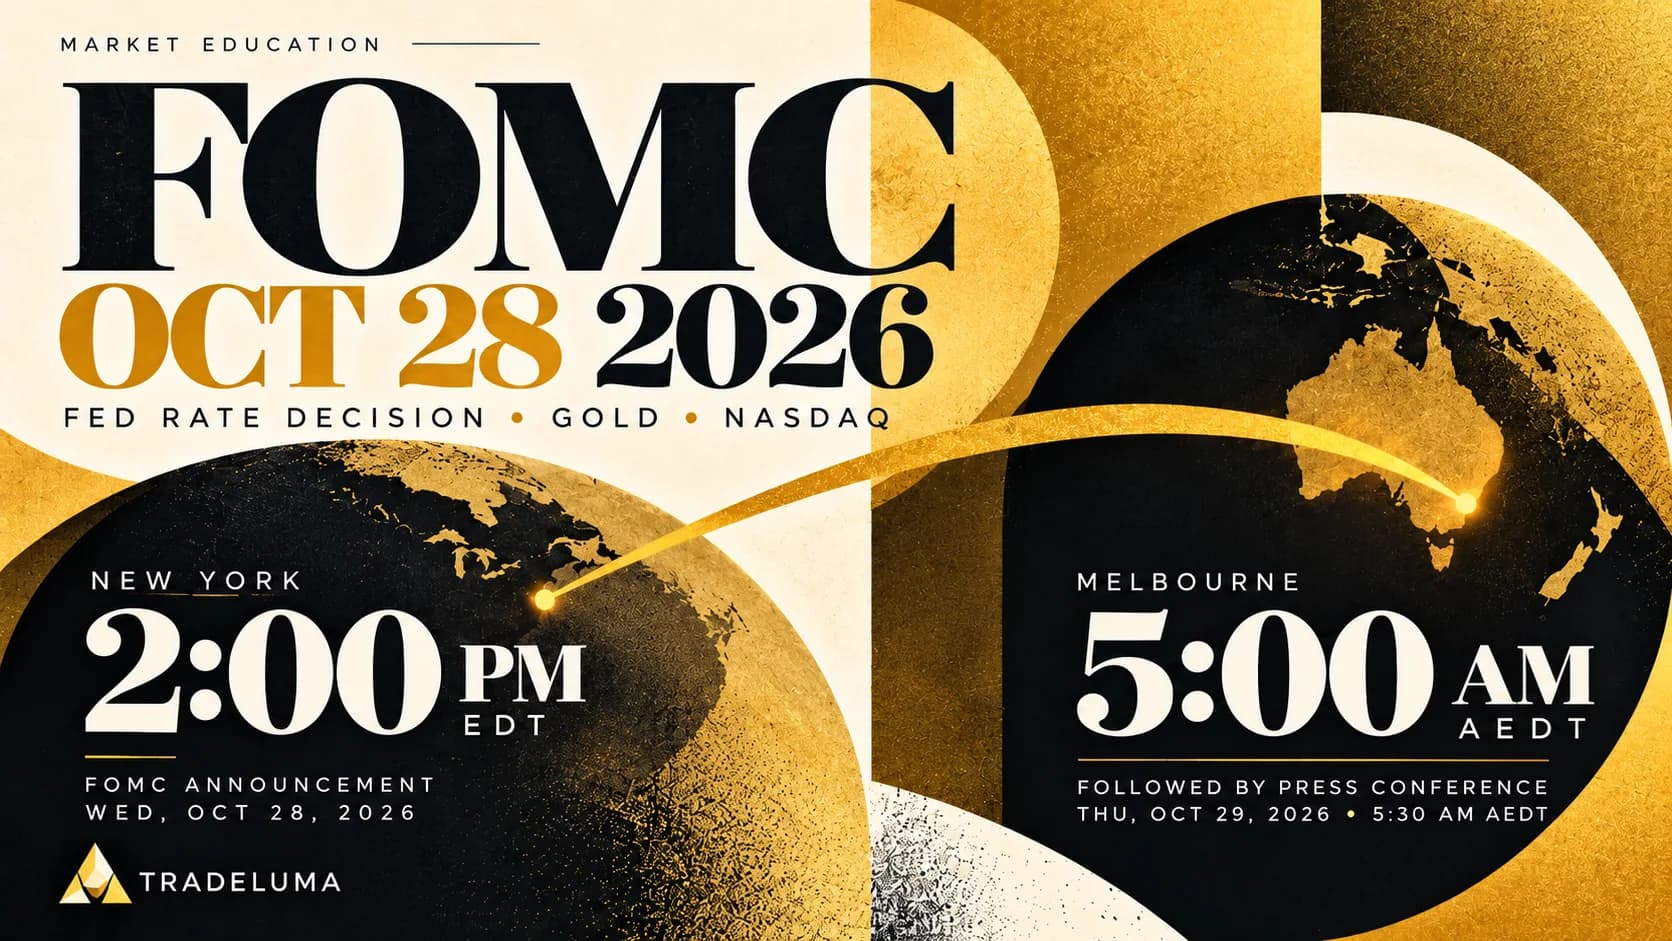
FOMC Meeting October 2026: Fed Rate Decision Time, Expectations & Gold/Nasdaq Impact
October 2026 FOMC decision time in New York and Australia, Fed rate expectations, statement and press conference explained, plus gold and Nasdaq trading risks.
US Treasury Yields Explained: 2-Year vs 10-Year, Yield Curve Inversion & Market Impact
Understand US 2-year vs 10-year Treasury yields, yield curve inversion, real yields and the potential impact on gold, Nasdaq and Treasury futures.