Futures
Nonfarm Payrolls (NFP) Explained: Why Jobs Data Moves Gold & Nasdaq
Learn what US nonfarm payrolls, wages, unemployment and revisions mean, and why NFP surprises can move gold, Nasdaq and Treasury futures.
On this page+
Nonfarm Payrolls (NFP) is one of the most closely watched economic releases for gold, Nasdaq and Treasury futures. Yet the headline job gain is only one piece of the US Employment Situation report: unemployment, wages, participation and prior-month revisions often change the market’s reading. This guide explains what NFP measures, how to interpret an actual-versus-forecast surprise, why gold and Nasdaq may react differently, and how to manage execution risk when liquidity becomes unstable.
What is Nonfarm Payrolls (NFP)?
Nonfarm payrolls is the closely watched monthly estimate of the number of paid jobs at US nonfarm employers. It appears in the Bureau of Labor Statistics (BLS) Employment Situation report, usually published at 8:30 a.m. Eastern Time on a scheduled Friday. Traders shorten the term to NFP or payrolls. The headline tells you how payroll jobs changed from the previous month after seasonal adjustment; it does not report how many different people found work.
NFP is useful because hiring can signal underlying demand, the business cycle, potential wage pressure and the possible path of US interest rates. It is not a trading signal in isolation. A release also includes unemployment, wages, hours, revisions and participation statistics, all of which can change the initial interpretation.
When is the next US jobs report?
As of 26 October 2026, the BLS calendar schedules the Employment Situation for October 2026 for Friday, 6 November 2026, at 8:30 a.m. US Eastern Time. Release dates and times can be changed; always check the current official BLS schedule rather than relying on an old article or a brokerage countdown.
Time-zone conversions need care. US daylight saving and Australian daylight saving change on different dates. Traders in Melbourne should convert the release date and time for the particular month, check their broker platform clock and avoid assuming the release always falls at the same local hour.
NFP is not the unemployment rate
The payroll headline comes from the BLS Current Employment Statistics establishment survey of businesses and government agencies. The unemployment rate comes from the Current Population Survey, a separate household survey. These surveys ask different questions, use different populations and have different sampling variability.
An economy can add payroll jobs while the household survey shows rising unemployment, especially when more people enter or return to the labour force. It is a mistake to treat that as a data error or to blend the two series into one payroll count.
What does the establishment survey measure?
The establishment survey counts payroll positions, not unique workers. Someone with two qualifying payroll jobs may be counted twice. It measures nonfarm wage and salary employment, including many government jobs; it generally excludes agricultural workers, the self-employed in unincorporated businesses, unpaid family workers and private household workers.
It also reports average hourly earnings, average weekly hours and industry breakdowns. These details can clarify whether growth is broad-based, concentrated in a few industries, or accompanied by changes in hours and pay.
What does the household survey measure?
The household survey classifies people as employed, unemployed or outside the labour force under BLS definitions. Its unemployment rate is the percentage of the civilian labour force without a job who are available for work and actively seeking work, with specific exceptions such as temporary layoff.
It covers types of work outside the payroll survey and provides participation and employment-population ratios. Household employment is a measure of people, not jobs, and monthly movements are noisier than the larger payroll survey. A large one-month difference between the two surveys does not automatically prove either series is wrong.
The five NFP figures to check first
A practical first pass is: headline nonfarm payroll change versus consensus; prior-month revisions; the U-3 unemployment rate; average hourly earnings month over month and year over year; and labour-force participation. Average weekly hours, industry distribution and the broader U-6 underutilisation rate add context.
Markets react to the information relative to what was priced in. Even a positive payroll print can be received as weak if consensus expected much more hiring, or if the prior two months are revised down sharply.
Actual versus forecast is more important than actual versus previous
A surprise is the reported number minus the market consensus forecast available just before the release. For example, if economists expected 150,000 new jobs and payrolls rose 210,000, the simple headline surprise is plus 60,000. That is a hypothetical example, not an actual October 2026 result.
Market prices may already reflect more than the published median estimate. Traders sometimes focus on the whole package, including wages and revisions, and on whether the release changes the expected Federal Reserve path. A positive surprise does not by itself predict the direction or size of a gold or Nasdaq move.
Why payroll revisions matter
Early establishment-survey estimates use the data available at the time. BLS routinely revises the two preceding months as additional employer responses arrive and seasonal factors are updated. Annual benchmark revisions also align levels more closely with unemployment-insurance tax records.
If the new payroll figure exceeds expectations by 60,000 but earlier months are revised down by a combined 70,000, the simple combined three-month arithmetic is negative 10,000 relative to those particular comparisons. That does not replace full economic analysis, but it illustrates why reading only the first headline may be misleading.
Average hourly earnings and wage inflation
Average hourly earnings (AHE) measure pay for covered private-sector employees in the establishment survey. Traders often compare monthly wage growth with consensus and check the twelve-month rate for context. Faster wage growth can add to concerns about services inflation, but the connection is not mechanical.
Changes in the composition of employment can affect the average: a shift toward higher-paying industries can lift average earnings without every worker receiving a large raise. The Federal Reserve evaluates a broader set of labour-cost and inflation indicators rather than treating one wage measure as a policy rule.
Unemployment rate: what a rise can mean
A higher unemployment rate can point to weaker labour demand, but it can also rise when people enter the labour force and begin looking for jobs. Read the unemployment rate alongside participation, household employment and the number unemployed.
The commonly quoted U-3 rate is narrower than U-6, which includes additional marginally attached workers and people employed part time for economic reasons. It is useful to know the definitions before using an unemployment headline to explain a market move.
Labour-force participation and employment-population ratio
The participation rate is the civilian labour force divided by the civilian noninstitutional population. The employment-population ratio is the employed share of that population. These indicators provide context for whether shifts in unemployment reflect hiring conditions, people looking for work, or both.
Demographic trends, survey changes and statistical noise can move them independently from the payroll headline. Avoid making a sweeping recession or boom call from a single monthly fraction of a percentage point.
How payrolls can change Federal Reserve expectations
The Fed has a dual mandate to promote maximum employment and price stability. Stronger-than-expected employment and pay may reduce market expectations for near-term rate cuts if inflation is still a concern. Weaker employment may make easing more plausible, especially if other activity indicators also soften.
The reaction depends on the starting point. In a growth scare, better employment may calm fears and support risk assets even as yields rise. In an inflation scare, the same payroll figure may weigh on stocks if traders infer a higher-for-longer interest-rate path. FedWatch probabilities reflect futures prices, not a promise from the Fed.
Why NFP moves Treasury yields and the dollar
Traders often express the initial macro interpretation in interest-rate markets. An upside surprise can push expected short-term rates and Treasury yields higher; the dollar may strengthen if US yields become relatively more attractive. A downside surprise can produce the reverse. Neither response is guaranteed.
Watch whether the yield move is concentrated in short-dated maturities or is broader, and whether the dollar agrees. Liquidity conditions, positioning and revisions can cause a reversal after the initial headline-driven burst.
Why gold futures may rise or fall after NFP
Gold pays no coupon, so its opportunity cost is often discussed in terms of real yields and the dollar. Strong payrolls that lift yields and the dollar can pressure gold futures; a weak report that brings yields down may support gold. Those are conditional relationships, not trading rules.
Risk aversion can change the story. A very weak labour report may prompt safe-haven demand, but traders can also liquidate gold during a liquidity squeeze. Compare price action with US yields, the dollar and broader positioning rather than assuming that “bad jobs equal higher gold.”
Why Nasdaq futures can react in either direction
Nasdaq-100 futures reflect expectations for large non-financial companies, many of which are sensitive to discount-rate changes. Strong employment may support growth and corporate earnings assumptions but simultaneously reduce expectations for interest-rate cuts. Which channel dominates can vary by regime.
A weak report may boost rate-cut hopes or intensify recession worries. MNQ and NQ may jump, reverse or whipsaw after different elements of the report are processed. A single surprise number cannot reliably tell you which outcome will occur.
What happens to ES, MES, NQ and MNQ at release time?
US equity-index futures may reprice rapidly as algorithms and discretionary participants respond to headline payrolls, unemployment and wage surprises. Quotes can update or disappear in milliseconds, and depth at the best bid or ask can thin. Prices may move far before a retail trader sees a stable chart candle.
MES tracks the S&P 500 futures contract in a smaller unit and MNQ tracks the Nasdaq-100 futures contract in a smaller unit. Smaller point values reduce dollar exposure per index point, but do not eliminate slippage, exchange halts, gaps or the danger of oversizing a volatile trade.
Worked example: NFP-day MNQ risk
MNQ has a $2 multiplier per Nasdaq-100 index point. In a purely hypothetical example, an 80-point adverse move against one MNQ contract corresponds to $160 of price movement before fees and slippage (80 × $2). Two contracts would double that exposure. These are contract arithmetic examples, not forecasts of typical NFP moves.
A stop entered 30 points away implies a planned $60 price risk for one MNQ contract if it executes exactly at the stop price. During a fast release, fill slippage can make the realised loss larger. The number of contracts should be sized to a loss budget that assumes imperfect execution.
Worked example: Micro Gold during payroll volatility
One Micro Gold (MGC) futures contract represents 10 troy ounces. In a hypothetical case, an $18 per-ounce gold move changes the value of one MGC position by about $180 before costs. Direction determines whether that is a gain or loss, and real fills may differ from the quoted move.
The same news release can shift both the expected rate path and demand for safe assets. Trade the contract specification and actual market conditions rather than inferring position size from a gold-chart percentage alone.
NFP, CPI and PCE: different economic signals
Nonfarm payrolls primarily describes US employment, although wages and hours provide information relevant to income and inflation. CPI measures price changes faced by urban consumers; PCE is the broader consumption-price measure used for the Fed’s two-percent longer-run inflation goal.
For SEO and trading education, these releases belong in a connected macroeconomic framework: payrolls help gauge labour-market resilience, CPI and PCE track inflation pressure, and Fed Funds futures reflect how market participants price prospective policy decisions. None should be analysed in isolation.
NFP versus ADP, JOLTS and unemployment claims
ADP private-sector employment estimates are compiled separately from official BLS payrolls and can differ materially in coverage and methods. JOLTS measures job openings, hires, quits and separations, while initial unemployment claims provide more frequent information on applications for unemployment benefits.
These releases may influence expectations before NFP but do not determine the official payroll result. Avoid treating a strong ADP print or a week of low claims as proof of the number that BLS will report.
Why the first candle can be misleading
An immediate spike may reflect participants reacting to the headline before reading wages, revisions and unemployment. Stop orders may trigger into thin liquidity, and quote spreads may widen. Subsequent repositioning can reverse the opening move, even if the initial interpretation was economically reasonable.
The one-minute, five-minute and fifteen-minute charts can tell different stories because the market is repricing information while liquidity is changing. A rule based on the direction of the first candle should be tested on true event-time data, not on smoothed historical candles.
A practical pre-release risk checklist
Before the release, confirm the BLS schedule and local time, instrument symbols, outstanding orders, stop/limit logic, maximum exposure and any broker-specific news-trading restrictions. Consider cancelling stale entry orders and choosing whether the system should pause entries, flatten exposure or run reduced size.
Know the difference between a stop-market order, which prioritises execution but not price, and a stop-limit order, which sets a price constraint but may not fill. A protective order is not a guarantee. Paper trading in normal conditions may underestimate event-time slippage.
NFP controls for automated trading strategies
An automated trading workflow should define event windows in the exchange or explicit timezone, enforce daily-loss and contract limits, prevent duplicate signals, monitor broker connectivity and reconcile the actual exchange-reported position. Pausing only the signal generator may not cancel broker-resident orders.
Predefine what happens when spreads widen, quotes become stale, an order is rejected, or a stop fails to fill. The system should log the event and avoid blindly resubmitting orders. Do not assume that a faster alert-to-broker connection provides a price guarantee during the news spike.
How to backtest a payroll-news strategy honestly
A credible NFP backtest requires historical release timestamps, the original payroll and wage data vintages, contemporaneous consensus expectations, and the prior revisions available at the time. Using today’s revised labour-market history introduces look-ahead bias. Include realistic spreads, depth and slippage.
Test across multiple volatility regimes and release outcomes, not just a few memorable gold or Nasdaq days. Separate pre-release positioning, the first minute and the post-release trend; strategy performance can differ sharply across windows. Paper testing and tiny controlled live exposure are not interchangeable.
Common mistakes traders make on NFP day
The most common mistakes are confusing jobs with people, ignoring revisions, equating higher unemployment with a recession, reading the forecast incorrectly, treating wage growth as the same as inflation and assuming every dollar or yield move translates cleanly into a gold signal.
Execution mistakes can be more expensive than interpretive ones: oversizing, placing stops inside the normal spike range, leaving unexpected working orders live, chasing the first candle and ignoring exchange/broker risk controls. A disciplined trader can choose not to participate in the first burst of volatility.
Key takeaway: read the whole labour-market picture
NFP is a high-impact report, not a magic directional indicator. Start with payrolls versus consensus and revisions; then read unemployment, participation, wages and hours. Ask how those surprises alter growth and interest-rate expectations relative to what futures prices already reflected.
For gold and Nasdaq, the path from economic data to price runs through yields, the dollar, earnings expectations, risk appetite and market positioning. TradeLuma focuses on execution discipline and visibility, not promising the direction of a news reaction. When liquidity is unreliable, choosing to sit out is a valid risk-control decision.
Frequently asked questions
What does NFP stand for in trading?+
Nonfarm Payrolls, the monthly US nonfarm payroll-employment change reported by the Bureau of Labor Statistics in the Employment Situation release.
When is the next NFP report after 26 October 2026?+
The BLS schedule lists Friday, 6 November 2026 at 8:30 a.m. US Eastern Time for October 2026 employment data. Verify the live BLS release calendar before trading.
Does NFP count people or jobs?+
The establishment survey counts qualifying paid payroll jobs, not unique people; a worker with more than one qualifying job can appear more than once.
Is unemployment measured in the same NFP survey?+
No. Payroll employment is estimated from the establishment survey, whereas the unemployment rate comes from a separate household survey with a different scope.
What is a good NFP number?+
There is no universally good figure. Interpretation depends on expectations, revisions, wage growth, unemployment and the economy’s current inflation and growth conditions.
What is an NFP surprise?+
The reported payroll change minus the consensus forecast just before the report. Compare the wage, unemployment and revision surprises separately as well.
Why can gold fall after a weak jobs report?+
Gold can fall if other factors dominate, such as a stronger dollar, liquidity stress, unwinding positioning or a different interpretation of wages and rate expectations. The usual yield relationship is not guaranteed.
Why can Nasdaq rise after strong payrolls?+
A strong labour market can ease recession worries and support earnings expectations. The positive growth interpretation may outweigh concern about higher interest rates in some market regimes.
Does an NFP miss guarantee a Fed rate cut?+
No. The Fed evaluates inflation and employment over time; market-implied probabilities can change quickly and are not policy commitments.
What are average hourly earnings in the jobs report?+
An establishment-survey estimate of average hourly pay for covered private-sector workers. Changes can reflect pay adjustments and shifts in the mix of jobs.
What is the difference between U-3 and U-6 unemployment?+
U-3 is the headline unemployment rate. U-6 is a broader measure that also includes some marginally attached people and part-time workers seeking full-time work.
Why are payroll numbers revised?+
BLS incorporates late employer responses, updated seasonal adjustments and annual benchmark information, so initial payroll estimates are routinely subject to revision.
Is ADP the same as the official NFP report?+
No. ADP measures private-sector employment using a separate methodology; it is not a substitute for the official BLS Employment Situation report.
Is NFP released every first Friday?+
Often, but not always. Check the official BLS schedule for exact dates, time zones and exceptions instead of assuming the first Friday every month.
How does one MNQ contract respond to an 80-point move?+
With a $2 per-index-point multiplier, an 80-point MNQ move equals $160 of price movement per contract before trading costs. The result can be a gain or loss.
Can a stop-loss guarantee my price on NFP day?+
No. Stop-market orders can experience significant slippage and stop-limit orders can remain unfilled. Liquidity may be thin and prices can gap.
Should an automated trading system pause for NFP?+
That is a risk-policy decision. A robust system should at least define the event window, limits, working-order behavior, rejection handling and broker-position reconciliation.
Can I backtest an NFP strategy using revised historical data?+
Revised data can introduce look-ahead bias. Use data as originally published, consensus expectations available then and realistic order-book or event-time execution assumptions.
Futures workflows
Explore the strategy side of TradeLuma.
Browse TradeLuma's futures strategy catalogue and the chart, rollover, and reference methodology used for each published strategy.
Explore futures strategies →Continue learning
Related guides.
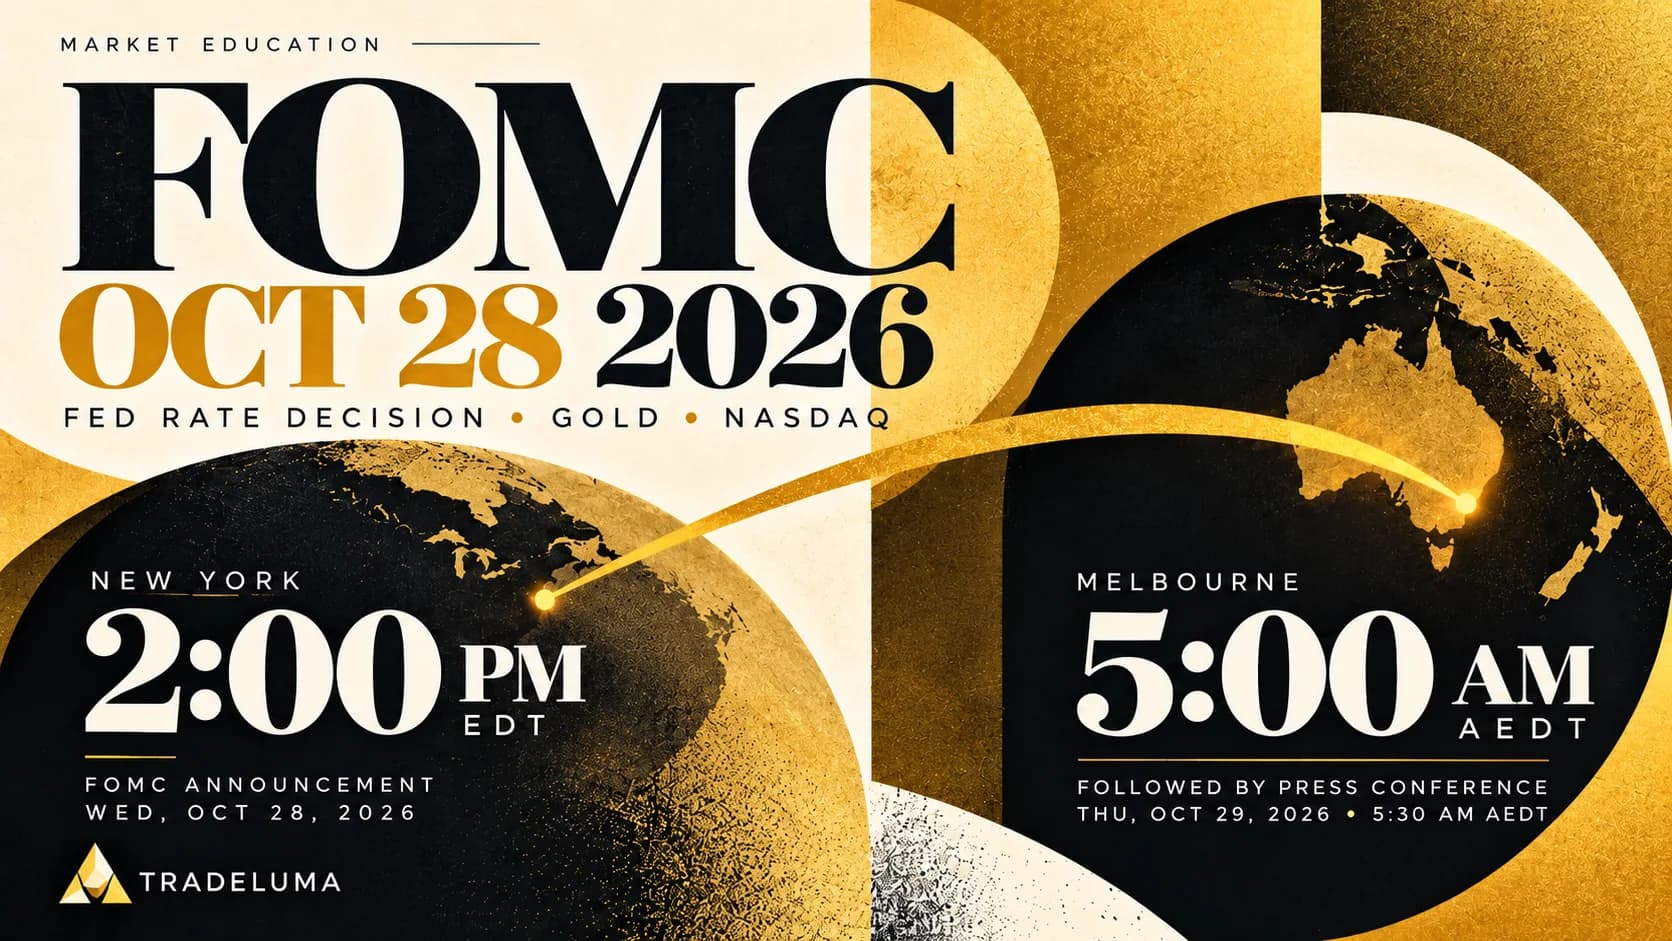
FOMC Meeting October 2026: Fed Rate Decision Time, Expectations & Gold/Nasdaq Impact
October 2026 FOMC decision time in New York and Australia, Fed rate expectations, statement and press conference explained, plus gold and Nasdaq trading risks.
CPI vs PCE Inflation Explained: Why Gold, Nasdaq & Futures React
Learn how US CPI and PCE inflation differ, what headline and core readings reveal, and why surprises can move gold, Nasdaq and Treasury futures.
US Treasury Yields Explained: 2-Year vs 10-Year, Yield Curve Inversion & Market Impact
Understand US 2-year vs 10-year Treasury yields, yield curve inversion, real yields and the potential impact on gold, Nasdaq and Treasury futures.