Bitcoin & Equity Markets
MSCI to Remove Strategy (MSTR): Could an $8.8 Billion Sell-Off Hit Bitcoin’s Biggest Treasury?
MSCI will remove Strategy from indexes after Nov. 30. Explore the $2.8B versus conditional $8.8B MSTR outflow estimates, Bitcoin impact and investor risks.
On this page+
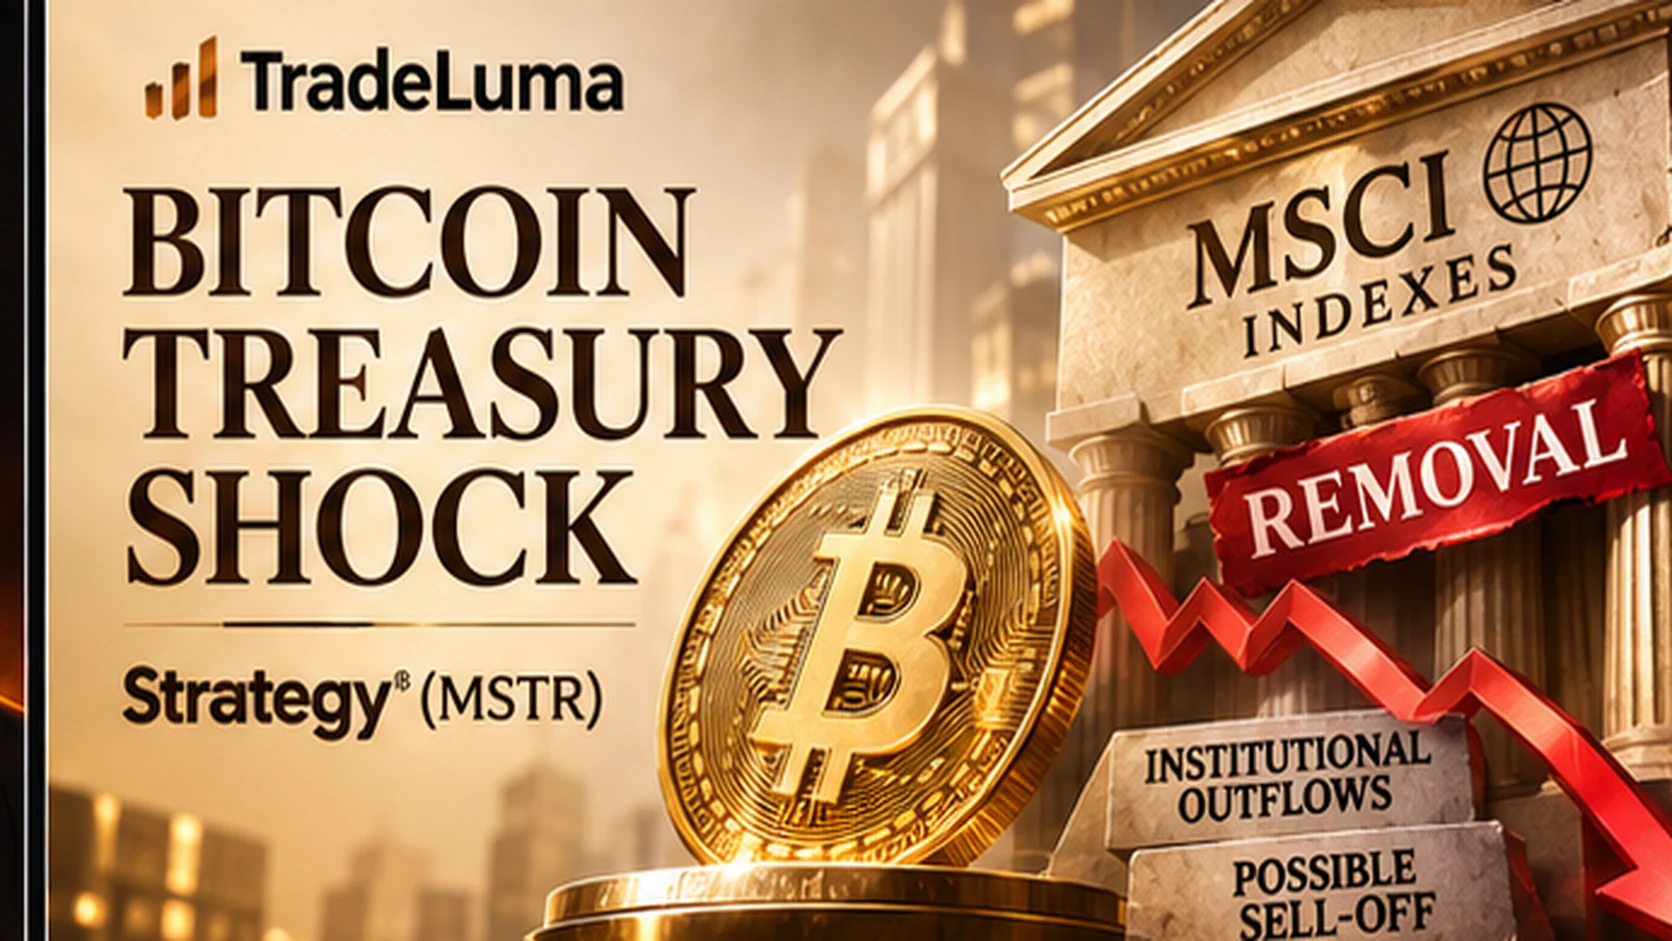
MSCI has confirmed that Strategy (NASDAQ: MSTR), Michael Saylor’s Bitcoin-treasury company, will leave affected equity indexes after the US market closes on November 30, 2026. The change takes effect on December 1. It is a real index-removal decision—not a Nasdaq delisting, not a ban on holding Bitcoin and not an order for Strategy to sell its coins. Yet the flow estimates have grabbed attention: Strategy had warned of approximately $2.8 billion of possible MSTR share sales, while JPMorgan estimated potential outflows as high as $8.8 billion if other major index providers followed MSCI. Those numbers describe scenarios, not sales that have already happened. Based on announcements and disclosures available by November 12, this guide explains the rule, identifies who might have to rebalance, separates stock-market pressure from Bitcoin liquidation risk, and maps the possible outcomes ahead of the November 30 close.
What MSCI actually announced on November 11, 2026
MSCI published the results of its November 2026 index review on November 11. Under the published implementation schedule, all announced changes will take effect after the close of trading on November 30, becoming effective on December 1. Strategy A appears among the deletions from the MSCI USA index. The public index lists are the decisive evidence that the constituent is scheduled to exit, while the precise composition of every index fund’s portfolio may differ.
A company can remain publicly listed and actively traded after leaving an index. Strategy is not being delisted from Nasdaq by this decision. Its operating business, securities, debt terms and Bitcoin custody are not cancelled by an index provider’s benchmark maintenance. The immediate issue is whether investors who seek to track MSCI indexes will need to replace their MSTR positions.
Why MSCI classified Strategy under its non-operating company rules
MSCI’s October 15 methodology decision widened ineligibility beyond traditional investment funds and business development companies. The index provider first screens for substantial operating assets. An issuer that fails the core screen faces five financial-ratio tests; a flag on four or more of the five can trigger ineligibility. Removal rules for existing constituents generally examine the most recent two annual reporting periods, with buffers intended to curb unnecessary turnover.
The new approach replaced temporary measures that had specifically scrutinised digital-asset treasury businesses whose holdings represented at least 50% of total assets. The resulting framework is wider than a simple Bitcoin percentage threshold. That is why it is misleading to say MSCI banned Bitcoin companies from all stock indexes or that every company holding crypto must be deleted.
The timeline: from consultation to the November 30 close
MSCI consulted investors on the treatment of non-operating companies in August, finalised the revised methodology on October 15 and announced the November review results on November 11. The next key date is the close of business on Monday, November 30, 2026; the changes are effective on Tuesday, December 1. The index-rebalance event is therefore in the future as of the period covered by this article.
Market participants may trade ahead of the effective close, and some funds use transition or sampling approaches rather than executing one enormous order at the final auction. For that reason, “MSCI will remove Strategy after November 30” is correct, but “all selling will occur at exactly one moment on November 30” is not established.
The $2.8 billion estimate: what it measures and what it does not
Strategy had previously highlighted approximately $2.8 billion in potential stock sales associated with MSCI exclusion. This is an estimate of index-linked MSTR equity flow, not a published tally of shares already sold. The estimate can change with Strategy’s stock price, index holdings, free-float treatment, fund replication, hedges and portfolio turnover before the rebalance.
A forecast of $2.8 billion in selling should not be translated into a $2.8 billion market-cap loss, a $2.8 billion Bitcoin sale or a guaranteed percentage decline in the share price. For every share sold, another investor can buy; the market impact depends on price elasticity, liquidity and where the new buyers are willing to transact.
Why JPMorgan’s $8.8 billion figure is a conditional worst-case scenario
Reuters reported a JPMorgan estimate of up to $8.8 billion in potential Strategy outflows if other index providers also adopt comparable exclusions. The conditional clause is essential. MSCI’s November announcement alone does not require funds tracking FTSE Russell, S&P Dow Jones Indices or other providers to change their portfolios.
Nor is the $8.8 billion figure necessarily an additional amount to place on top of the $2.8 billion estimate. They refer to different assumptions and potentially overlapping sets of holdings. Adding them together without checking their methodologies could double-count the same underlying exposure. The credible headline is that broader imitation could intensify pressure, not that a verified $8.8 billion order has entered the market.
Which holders may sell MSTR, and why timing is uncertain
A passive fund tightly tracking an affected MSCI equity benchmark would ordinarily adjust its portfolio to reflect deletion. Other investors, including discretionary active managers, benchmark-aware managers and arbitrage desks, may choose to trade before, during or after the implementation period. A fund that tracks a different benchmark has no automatic obligation to sell simply because MSCI changed its own membership list.
The most visible market microstructure could emerge around November 30, but trading pressure can be dispersed across the preceding sessions. Some investors may short the stock in anticipation of rebalancing, while others may buy if a large discounted block appears. These interactions can create short-lived volatility without providing a predictable trading edge.
MSCI removal is not a forced sale of Strategy’s Bitcoin holdings
The direct mechanical transaction is a sale of MSTR shares by holders who no longer need them for index replication. Those shares change hands on an equity venue. The transaction does not pull Bitcoin out of Strategy’s wallets or automatically generate a corporate margin call. Shareholder selling and corporate treasury decisions belong to separate balance sheets.
A secondary link is possible over time: if the stock falls, the company’s ability or willingness to raise new equity may diminish. Lower financing capacity could slow future Bitcoin purchases, and a sustained liquidity or liability problem could influence treasury choices. But an MSCI deletion by itself does not establish that Strategy must liquidate BTC. Distinguishing immediate share flows from later funding consequences is the most important analytical step.
How much Bitcoin does Strategy own?
In its November 9 public disclosure covering the period through November 8, Strategy reported 850,364 BTC purchased at an aggregate cost of about US$64.16 billion, or approximately US$75,456 per coin inclusive of fees and expenses. During the November 2–8 period, it bought another 1,036 BTC for approximately US$81.9 million. These are company-reported holdings and historical purchase costs, not a current fair-market valuation or a claim about future purchases.
The large position makes Strategy particularly sensitive to Bitcoin prices and to market sentiment about its financing structure. However, the company also has a software business, different classes of securities and dollar-denominated assets or liabilities. Comparing MSTR’s equity value mechanically with the headline Bitcoin balance alone would omit important components of its capital structure.
Why MSTR can fall faster than Bitcoin—and also sometimes rebound faster
MSTR is not a spot Bitcoin unit or a Bitcoin ETF. It is common equity in a company with capital-market financing, operational activities, management decisions and other shareholders. It can react to BTC moves, but its performance also depends on changes in the equity risk premium, perceived financing optionality, issuance expectations and demand for a leveraged-looking Bitcoin proxy.
That mixture can magnify both upside and downside. A decline in Bitcoin could weaken the value attributed to the treasury, while MSCI-specific equity selling independently reduces demand for the shares. Conversely, a rebound in crypto prices or renewed demand for the stock could offset some index pressure. Historical beta or premium relationships are unstable and should not be treated as a fixed multiplier.
Metaplanet and other asset-heavy companies: a broader index change
Japan-listed Metaplanet was also named among firms affected in the November review, while Reuters identified the UK uranium investor Yellow Cake as another example. Those cases highlight that MSCI is evaluating non-operating and fund-like characteristics across asset categories, not singling out Bitcoin ownership as automatically disqualifying.
The classification of one firm cannot be mechanically extended to every digital-asset-treasury company. For example, contemporary reporting indicated that Ethereum treasury firm SharpLink was on a watchlist but not among the November small-cap deletions. Investors need to consult the specific index and deletion list for each ticker.
Bitcoin’s price reaction: separate macro weakness from MSCI news
The MSCI decision landed while Bitcoin was already struggling with the effects of higher US rate expectations and broader risk aversion. News reports on November 12 placed Bitcoin around US$73,600–US$74,000 in different early-day observations, with prices varying by venue and timestamp. These are dated snapshots, not live quotes, and should not be read as a November 13 closing level.
It is tempting to blame every crypto move on the index announcement. A more rigorous approach tracks whether BTC and MSTR move together, whether MSTR underperforms against its Bitcoin exposure, and whether developments in Treasury yields, dollar strength, ETF flows or regulatory policy are occurring simultaneously. Several catalysts can influence a volatile market in the same session.
The next trading catalysts and what to watch until November 30
First, monitor any statements from other index providers. Wider exclusions are the condition that makes the larger JPMorgan outflow scenario relevant. Second, monitor Strategy’s own disclosures about capital raising, outstanding securities, Bitcoin purchases or sales, liquidity and any responses to the MSCI review. Third, watch late-November MSTR volumes, spreads, closing-auction activity and short-interest indicators without assuming any one metric proves forced liquidation.
Finally, keep broader crypto and rates events on the calendar. BTC itself trades continuously, while Nasdaq-listed MSTR has separate regular and extended stock-market sessions. Price gaps, weekend news and differing liquidity profiles make market orders, leverage and pre-announcement positioning especially risky.
Three scenarios for MSTR, Bitcoin and the rebalance
Bearish equity scenario: index-sensitive investors exit while new demand is weak, compressing MSTR’s relative valuation. If financing becomes more expensive, expectations for new corporate Bitcoin purchases may weaken. This scenario does not require an immediate sale of existing BTC holdings, but simultaneous weakness in BTC could deepen the stock’s drawdown.
Balanced scenario: much of the MSCI decision was anticipated, sales are distributed over time, and new investors absorb the shares at prices already reflecting the change. MSTR may be volatile around the November 30 close without a prolonged sell-off. Bitcoin could respond more to macro conditions than to this index event.
Bullish relief scenario: the estimated rebalancing demand proves smaller or is absorbed more efficiently than feared, competing index providers do not follow MSCI, and investors refocus on Bitcoin price, financing capacity and corporate results. The share price could recover even though the MSCI deletion still takes effect. These are conditional possibilities—not forecasts with measured probabilities.
A practical risk checklist for traders watching MSTR and BTC
Before acting, specify whether the instrument is MSTR common stock, a Bitcoin ETF, spot BTC, an options contract or a futures product. Each has a different price driver, trading session and liquidation mechanism. Confirm the exact scheduled catalyst and the timestamp of any quote; market headlines often mix an official closing price, an after-hours trade and a crypto exchange’s twenty-four-hour quote.
Plan maximum position risk and avoid assuming that a heavily publicised rebalance produces a free short. Known events attract anticipatory positioning, and a short squeeze or unusually large closing-auction volume may reverse an apparently obvious move. Do not treat $2.8 billion or $8.8 billion as a guaranteed executable flow, a stop-loss distance or a target. Review fills, fees, slippage and concentration rather than relying on a dramatic headline.
What the MSCI decision means for the future of Bitcoin treasury stocks
The wider question is whether public-market investors should value companies primarily for their operating economics or treat their treasury assets as a primary exposure. MSCI is drawing its eligibility boundary using operating assets and financial ratios. Corporate treasury firms argue that this can penalise an emerging capital-allocation business model; benchmark designers argue that equity indexes should not simply duplicate passive investment vehicles.
Neither side settles the investment question for an individual shareholder. Future capital-market access, corporate governance, Bitcoin price volatility and index-provider policies can all change the relative appeal of MSTR and other treasury names. The most durable insight is that a stock can carry both crypto-market risk and an independent equity-market eligibility risk. An index decision is important precisely because those are two different layers of exposure.
Bottom line: the index removal is real, the $8.8B Bitcoin-sale narrative is not
Strategy is scheduled to be removed from affected MSCI benchmarks after the November 30, 2026 close. That can prompt some passive holders to sell MSTR shares and may influence the future attractiveness of equity financing. But the company has not been directed by MSCI to sell its Bitcoin, and the $8.8 billion headline depends on other index providers following a similar path.
A useful investment or trading plan begins by keeping the units straight: MSTR equity shares, dollars of potential fund flows, BTC owned by the company, and actual BTC trading volume. The first is directly involved in MSCI rebalancing; the others require additional assumptions and evidence.
Frequently asked questions
Is Strategy (MSTR) being delisted from Nasdaq?+
No. MSCI announced removal from affected equity benchmarks after the November 30, 2026 close. MSTR remains a Nasdaq-listed stock unless a separate exchange action occurs; none is implied by this index review.
When will MSCI remove Strategy?+
MSCI said its November 2026 index-review changes will be implemented after the close of business on November 30, 2026 and effective December 1. The change is not an already completed rebalance as of November 12.
Will $8.8 billion of Strategy shares definitely be sold?+
No. Reuters reported a JPMorgan estimate of potential outflows up to $8.8 billion if other index providers followed MSCI. It is conditional and should not be confused with confirmed MSCI-only trading.
What does the $2.8 billion estimate mean?+
It is a previously discussed estimate of possible MSTR equity sales associated with MSCI exclusion, not a definitive market order and not $2.8 billion of company-owned Bitcoin.
Does MSCI removal force Strategy to sell Bitcoin?+
No. Fund rebalancing involves outside shareholders selling MSTR stock. It does not mechanically instruct Strategy to sell BTC. Indirect financing pressures are possible but must be supported by separate evidence.
How much Bitcoin did Strategy report owning?+
As of November 8, 2026, Strategy reported 850,364 BTC acquired at an aggregate purchase cost of roughly $64.16 billion, including expenses. This is a dated holding disclosure, not a current market valuation.
Is Metaplanet also affected?+
Yes. November 2026 reporting and the MSCI review identify Japan-listed Metaplanet among companies affected by the new non-operating-company eligibility screens.
Are all Bitcoin and Ethereum treasury companies removed?+
No. MSCI applies a general non-operating-company methodology, which considers operating assets and five financial ratios. Each issuer must be checked against the specific published deletion or watchlist.
Why can MSTR and Bitcoin move differently?+
MSTR is a listed corporation with financing, share supply, other securities and equity-market flows. BTC is a separately traded crypto asset. MSCI deletion directly affects MSTR index demand, not Bitcoin ownership transfer.
What should traders watch ahead of November 30?+
Follow index-provider announcements, Strategy disclosures, MSTR trading volume and closing-auction liquidity, BTC prices, rates and the US dollar. Use dated prices and predefined risk rules rather than treating flow estimates as guaranteed returns.
Put it into practice
Use the risk maths next to the guide.
Open TradeLuma's free position-size, risk/reward, expectancy, and drawdown tools to test the numbers behind a risk-management decision.
Open free trading calculators →Continue learning
Related guides.
GTA 6's $8.2 Billion Gamble: Record Preorders, an Earnings Miss and the TTWO Stock Countdown
GTA 6 preorders near 7.71M in third-party estimates as Take-Two reports a Q2 bookings miss. Explore TTWO stock, $8.2B FY27 guidance and Nov 19 launch.
SoftBank's $7 Billion AI Nightmare: Masayoshi Son's $64.6 Billion OpenAI Bet Faces a Reckoning
SoftBank swung to a ¥1.12T ($7.1B) quarterly loss as US data-centre charges hit $3.7B and financing costs jumped. What happens to its $64.6B OpenAI investment and 9984 stock?
Anthropic's $69.3 Billion IPO Proposal Was Withdrawn: What Changed?
Updated 11 Nov: Anthropic retracted the $69.3B draft and filed a new $70–$78 IPO range, up to $64.35B. Historical Nov 10 analysis of AI compute economics.