AI Stocks & Markets
SoftBank's $7 Billion AI Nightmare: Masayoshi Son's $64.6 Billion OpenAI Bet Faces a Reckoning
SoftBank swung to a ¥1.12T ($7.1B) quarterly loss as US data-centre charges hit $3.7B and financing costs jumped. What happens to its $64.6B OpenAI investment and 9984 stock?
On this page+
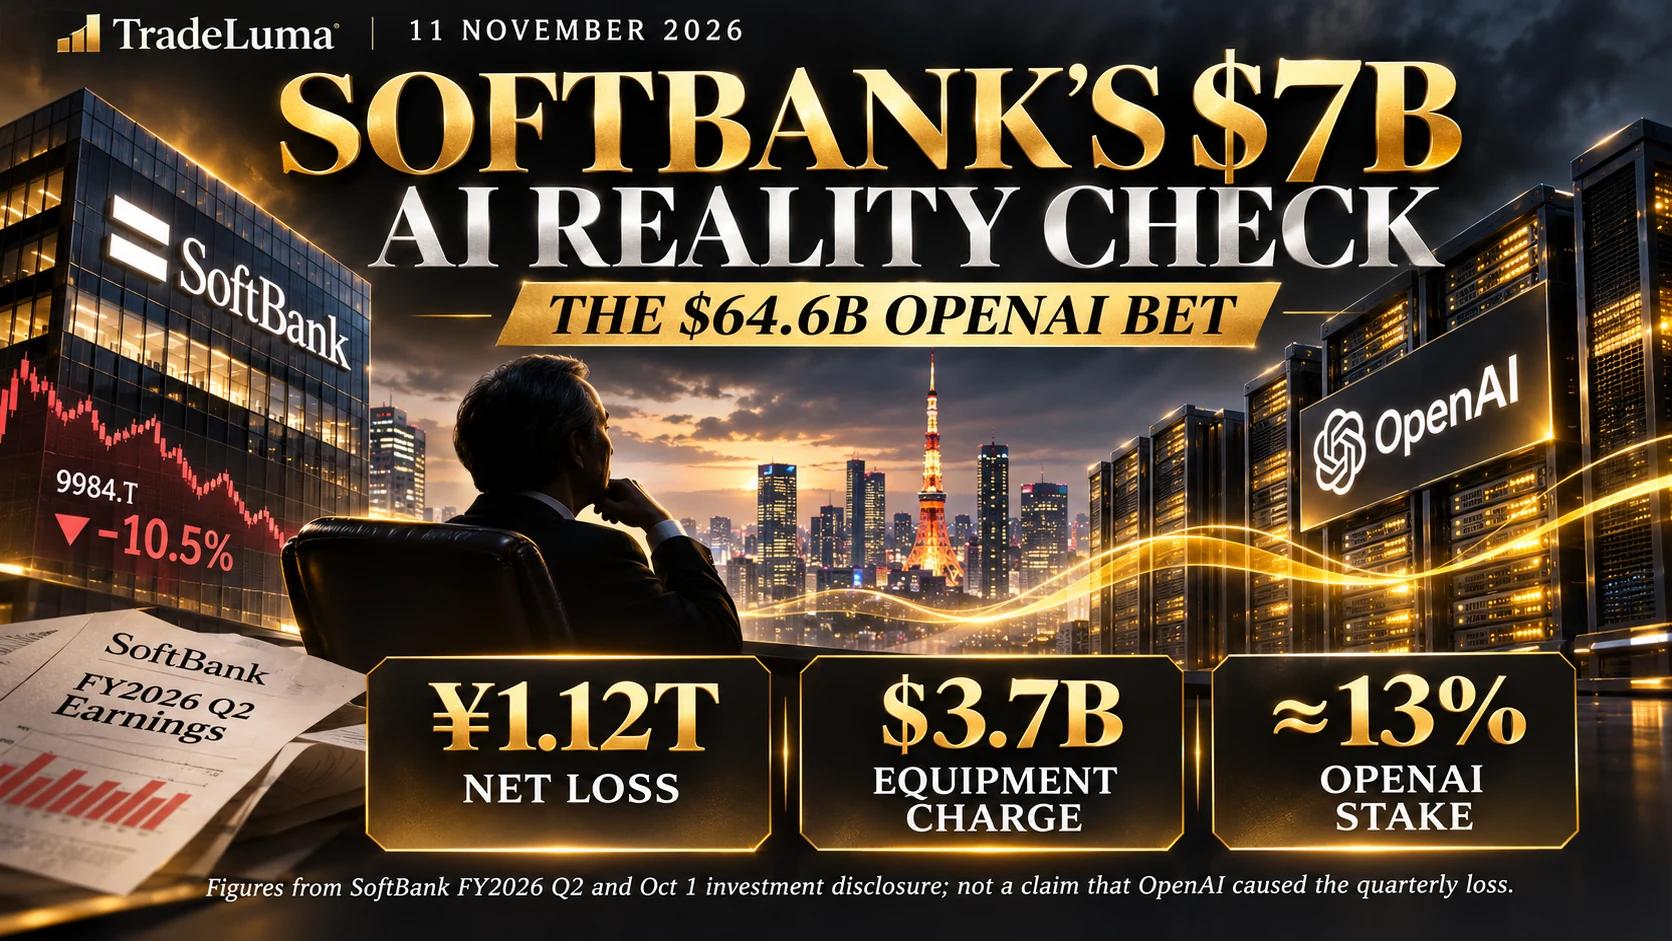
Masayoshi Son's AI empire has met an uncomfortable reality check. On November 10, 2026, SoftBank Group reported a ¥1.12 trillion (approximately US$7.1 billion) fiscal second-quarter net loss. The shock was not an OpenAI writedown alone: it reflected a US$3.7 billion charge associated with revised American data-centre equipment procurement, higher financing costs and a volatile portfolio. SoftBank shares fell as much as 10.5% intraday on November 11. At the same time, the company has confirmed US$64.6 billion of cumulative investment for roughly 13% of OpenAI. Can the assets grow quickly enough to justify the financing and construction risks? This is the investment question beneath the headline.
The $7 billion shock: what SoftBank actually reported
SoftBank Group’s November 10, 2026 financial results landed with a number even seasoned technology investors could not ignore: a fiscal second-quarter net loss attributable to owners of about ¥1.12 trillion, roughly US$7.1 billion at contemporaneous exchange rates. The July–September result reversed a profit of about ¥2.50 trillion in the corresponding quarter a year earlier. Analysts had expected a materially better outcome. The market’s immediate question was not merely how big the loss looked, but what it revealed about the financing of the global AI buildout.
The following day, SoftBank Group shares in Tokyo (9984) fell as much as 10.5% intraday. That is a real market reaction, but it should not be mistaken for an exact closing return: intraday lows, delayed quotes and final closes are different observations. Our analysis uses the latest November 11 reporting available at publication and never treats a hypothetical stock chart in the cover artwork as exchange data.
The headline is about SoftBank Group Corp., the investment holding company. It is not the separately listed Japanese telecommunications operator SoftBank Corp. Their reports and ticker symbols are not interchangeable.
Net loss, cash burn and an investment write-down are not synonyms
The ¥1.12 trillion quarterly bottom-line loss reflects accounting recognition across investments, operations, financing and exceptional costs. It does not establish that SoftBank physically spent US$7.1 billion in cash during the quarter, nor that its OpenAI stake itself lost that entire amount. A large provision, asset impairment or mark-to-market movement can reduce earnings without creating an equal cash payment at that moment. Conversely, borrowing to fund investments can increase cash balances while exposing the group to future interest obligations.
This distinction matters especially for an investment conglomerate with privately held assets and financing backed by listed securities. SoftBank’s valuations can change sharply between reporting periods, while some financing costs and cash commitments are more predictable. A responsible investment thesis should track net debt, collateral, liquidity and future capital commitments alongside reported profit. One headline figure cannot replace that work.
The $3.7 billion equipment charge: the crucial detail
SoftBank disclosed a charge of about US$3.7 billion relating to advance payments for power-generation and other equipment planned for US AI data-centre projects. Management said elements of its procurement strategy were revised after equipment and capacity had been reserved ahead of final specifications. In a rush to secure power, turbines and infrastructure slots, some advance payments could not simply be refunded when the plans changed.
The charge relates to US projects including a large development in Pike County, Ohio. It does not, by itself, prove that the entire data centre has been cancelled or that an announced gigawatt target has been abandoned. Reports indicate that SoftBank is reassessing procurement rather than declaring a wholesale retreat from AI infrastructure. That narrower conclusion is important: a write-down can be a costly tactical reset without being an admission that the long-term market for AI computing has disappeared.
Could the $2.1 billion rebate cushion the impact?
SoftBank said it may qualify for rebates of up to approximately US$2.1 billion against future equipment purchases. A prospective rebate is not the same as a US$2.1 billion refund already received or a guaranteed reversal of the reported charge. It depends on later purchases, terms and execution. Investors should therefore distinguish a plausible offset from an immediately collectible receivable.
Even if rebates materialise, they would not erase the operational lesson: spending committed years in advance can become stranded when project specifications, financing assumptions or power-market conditions shift. The market will look for evidence of tighter contracting discipline, particularly around non-refundable deposits and complex infrastructure packages.
Why power, not just GPUs, is the bottleneck
AI data centres require far more than accelerators. Power generation, grid access, substation equipment, cooling, transmission, networking, construction and backup capacity all have to arrive in a workable sequence. A GPU cluster can be commercially attractive in a spreadsheet but unproductive if a single critical electrical component arrives late. Developers have responded to long lead times by booking capacity early, paying deposits and sometimes accepting contract rigidity.
That creates an uncomfortable trade-off. Securing equipment today can protect a project from shortages tomorrow; committing before designs mature can also crystallise expensive changes. SoftBank’s equipment loss is a vivid case study in that tension. For investors, the real indicator is not a press release boasting about megawatts or gigawatts. It is how much usable, energised capacity is delivered on schedule, under contracts that earn adequate returns after financing costs.
Financing costs more than doubled to ¥462 billion
Reuters reported that SoftBank’s financing costs reached approximately ¥462 billion in the July–September quarter, more than double the year-earlier figure. This is one of the most important numbers in the entire report. Interest and financing charges can keep accruing even when investments are illiquid, valuations wobble or data-centre commissioning slips. If the cost of capital rises while expected cash flows are pushed into the future, the economic margin for error shrinks.
The ¥462 billion is a reported quarterly financing-cost figure, not a yield applied equally to every loan and bond. Borrowing instruments differ by maturity, security, currency, floating versus fixed coupon and embedded collateral rights. Investors should seek a maturity ladder and interest-cost breakdown rather than treating a single blended number as the cost of all new projects.
$56.5 billion raised in a quarter: funding is not revenue
SoftBank said it raised approximately US$56.5 billion through financing activity during the quarter, a group record. That figure is not operating revenue, a fresh profit stream or entirely incremental free cash. It describes funding raised through instruments such as loans and bonds, some of which can replace, refinance or bridge earlier obligations. The group reported, among other activity, a roughly US$11.87 billion term loan, US$10 billion dollar bond issuance and a ¥1 trillion yen-denominated bond issue.
The central question is what this capital buys and when the assets produce distributable cash flows. Borrowing to purchase a rapidly appreciating stake can appear sensible while valuations climb. Borrowing to fund a facility whose completion slips can be more difficult, because interest starts ticking before customers pay. Both activities may appear under the umbrella of “AI investment,” but they have very different risk profiles.
The Arm margin loan and collateral feedback loop
SoftBank expanded a margin loan backed by its stake in chip designer Arm to around US$25 billion, according to market reporting. This is structurally different from unsecured corporate debt: the lender’s security is linked to the value and liquidity of pledged shares. A drop in collateral value can reduce financing flexibility or trigger contractual requirements, depending on thresholds and covenants. It does not mean SoftBank automatically faces a margin call after any particular Arm price decline.
Arm remains a major SoftBank portfolio asset and an important source of economic exposure to semiconductor demand. The danger in collateralised borrowing is a feedback loop during a broad technology sell-off: equities weaken, available collateral headroom narrows, and refinancing becomes less attractive at precisely the moment a capital-intensive business would prefer flexibility. Track disclosed terms and leverage metrics, not dramatic assumptions about forced sales.
The $64.6 billion OpenAI investment: what the disclosure says
On October 1, 2026, SoftBank Group publicly confirmed a third and final US$10 billion tranche of its announced US$30 billion follow-on investment in OpenAI Group PBC. That brought its cumulative investment to US$64.6 billion and its approximate ownership interest to 13%. The final tranche was funded by proceeds of foreign-currency-denominated senior notes. SoftBank also said the earlier bridge facility had been fully repaid, with the remaining US$10 billion undrawn capacity cancelled.
The official date matters: the final US$10 billion tranche was executed October 1, just after the September 30 fiscal-quarter end. Analysts should avoid attributing every subsequent cash movement directly to the July–September period. The US$64.6 billion describes cumulative invested capital, not the current fair market value of the 13% stake, and not an estimate of SoftBank’s potential loss if OpenAI were revalued.
Why a 13% stake can dominate the narrative
OpenAI is a powerful source of upside because the market attaches enormous expectations to frontier AI models, developer platforms, enterprise subscriptions and agentic software. But concentration works in both directions. Even if the operating businesses and portfolios remain diversified, investors may increasingly treat SoftBank shares as a levered way to express confidence—or scepticism—about OpenAI and the broader AI ecosystem.
That does not mean SoftBank and OpenAI have identical financial results. OpenAI is a private portfolio investment; SoftBank reports the consolidated result under its own accounting framework. Exposure also includes Arm, Vision Funds, infrastructure assets and liabilities. Questions about OpenAI’s future profitability matter to SoftBank’s asset value and financing confidence, but an adverse quarter at SoftBank cannot simply be labelled an OpenAI loss.
AI infrastructure spending and the danger of circular expectations
The AI investment chain is interconnected. Model developers forecast escalating compute demand; infrastructure operators build capacity; chip suppliers and power vendors sell equipment; financiers lend against projected earnings or collateral; investors capitalise the eventual software and compute revenues. Strong demand can make each step sensible. Yet when multiple parties rely on the same future expansion in AI spending, a slowdown can pressure several links simultaneously.
SoftBank’s equipment charge demonstrates how practical engineering and contracting risks can surface even before customer demand is the central issue. The market should not treat every announced AI purchase order as equal to contracted, paid, profitable end-user demand. Useful questions include who guarantees utilisation, whether contracts can be cancelled, how depreciation is funded and which entity ultimately absorbs overruns.
Loan-to-value was 15.9%: a buffer, not a promise
The same official SoftBank asset-value update put its loan-to-value ratio at 15.9% on September 30. The ratio suggests SoftBank had collateral and asset-value headroom at that reporting date, and management has discussed risk disciplines around leverage. The figure does not establish that subsequent stock-market declines leave the ratio unchanged, or that all subsidiary debt and off-balance-sheet commitments are captured in the same way.
LTV is a snapshot, not a cash-flow forecast. The right follow-up questions are how much debt is due within one, three and five years; the composition of liquid versus private holdings; restrictions on pledged assets; cash at the holding company; and the possible impact of currency moves. A company can have a respectable reported LTV and still face a costly funding environment.
How Vision Fund exposures complicate the earnings picture
SoftBank’s funds own stakes in private technology businesses and listed companies across sectors. Their reported performance can reflect both realised exits and unrealised fair-value changes. An investment gain in one segment does not ensure consolidated profit, just as a fund-level loss does not necessarily equal group-wide operating deterioration.
Investors should distinguish three layers: underlying investee performance, the price at which SoftBank marks or sells that stake, and financing costs or corporate expenses borne above the fund. The same macro shock can alter each layer in different ways. This is why a one-quarter SoftBank net loss is a poor stand-alone estimate of AI demand, but a valuable prompt to examine project economics and debt discipline.
Could a future OpenAI IPO solve the problem?
An eventual public listing for OpenAI could provide an observable market valuation and, after any applicable lockups and liquidity restrictions, potential avenues to realise part of SoftBank’s holding. But as of November 11, 2026, an OpenAI IPO was not a completed transaction, and no cash proceeds from such an exit can be assumed in this quarter’s financing analysis. Reported future plans or valuations are not a binding liquidity guarantee.
Even a successful IPO would leave questions about the cost basis, share classes, actual sale windows and tax consequences. A buoyant OpenAI valuation could support SoftBank’s NAV and borrowing capacity; a weaker offering could pressure both. The right framing is an optional future catalyst, not a ready-made bailout.
The knock-on effects for Arm, Nvidia and AI-cloud providers
The SoftBank story can influence sentiment toward Arm because of collateralised lending and portfolio exposure; toward Nvidia and AI server suppliers because of infrastructure orders; and toward AI-cloud operators such as CoreWeave because large computing projects require reliable finance, power and customer demand. These relationships are not direct proof that one company’s reported charge will become another company’s revenue or loss.
TradeLuma’s earlier CoreWeave analysis explored the separate issue of cloud infrastructure debt and secured borrowing. Read it at https://tradeluma.app/blog/coreweave-stock-crash-ai-debt-crisis-earnings-2026. Together, the cases suggest a useful sector-level question: what happens when the cost of finance rises faster than contracted compute revenue? The answer will vary by balance sheet, lease terms and customer quality.
The inflation backdrop makes refinancing harder
The November 10 US inflation surprise put pressure on duration-sensitive assets and lifted Treasury yields. When risk-free yields rise, investors often demand more return from corporate bonds and speculative assets too. A global borrower funding dollar-denominated AI projects can face the combined pressure of higher reference rates, larger credit spreads, collateral volatility and currency fluctuations.
This is not a claim that the CPI release caused every component of SoftBank’s Q2 loss; the quarter ended September 30, before the November data release. It is a forward-looking market risk that investors must monitor as the company rolls over financing and commits to additional capital expenditures. TradeLuma’s US inflation analysis is here: https://tradeluma.app/blog/us-inflation-shock-november-2026-gold-fed-rate-hike.
Bull case: a painful but manageable reset
In the optimistic scenario, a one-off procurement reassessment clears legacy mistakes, much of the potential equipment rebate becomes useful on later orders, and large AI customers continue to sign sufficiently profitable long-term agreements. OpenAI and other holdings appreciate faster than financing costs, projects energise on schedule, and SoftBank maintains ample liquidity and collateral headroom.
That outcome would not require the November headline loss to disappear. It would require management to demonstrate that the loss was bounded, cash commitments are being brought under control and the next wave of investments produces more transparent returns. An improved risk premium could then support both the portfolio valuation and SoftBank shares.
Base case: growth continues, but the funding discount remains
The central scenario is neither an AI collapse nor an effortless rebound. Demand for training and inference may remain strong while the cost of capital, electricity and construction makes project-level returns uneven. Some assets could rise in value, others could suffer impairments, and SoftBank shares could trade at a persistent discount to reported NAV because investors assign a meaningful risk charge to leverage and private valuations.
Under this scenario, cash management, measured project commissioning and the maturity schedule matter more than an eye-catching announcement about model capability. The stock can be volatile even when long-term AI adoption continues.
Bear case: collateral, delays and refinancing reinforce one another
The downside scenario begins when weaker technology valuations reduce borrowing headroom at the same time as large projects require more capital and financing becomes expensive. Construction delays push customer cash generation further into the future. If unexpected write-downs recur or private valuations are revised lower, investors may demand an even higher return to hold SoftBank debt and equity.
None of that is predetermined by one reported quarterly loss. It is a scenario to stress-test, not a prediction of bankruptcy, a guaranteed margin call or a confirmed collapse in OpenAI’s value. The practical purpose is to identify which disclosures could establish whether the risk is developing.
A trader’s November 11 checklist: what to monitor next
First, monitor SoftBank’s official follow-up disclosures on project procurement, possible rebates and the cash cost of power infrastructure. Second, track the holding company’s financing costs, cash, net debt, loan-to-value and Arm-backed margin-loan terms. Third, observe whether OpenAI’s valuation and financing announcements are accompanied by audited revenue quality, margins and credible cash-flow economics. Fourth, compare short- and long-term borrowing rates and any changes in credit spreads.
Finally, separate SoftBank Group’s 9984 Tokyo share price from SoftBank Corp.’s unrelated telecom ticker. A gain or loss seen in an indicative delayed quote is not necessarily the final closing result. This article is general market commentary, not personalised investment advice, and its scenarios are not price targets.
Bottom line: the AI boom has a financing test, not just a technology test
The US$7.1 billion quarterly loss is striking, but its significance lies in the mechanisms underneath: about US$3.7 billion of revised equipment-related charges, sharply higher financing costs and an aggressive programme of infrastructure and private AI investment. SoftBank’s confirmed US$64.6 billion cumulative investment in OpenAI for roughly 13% ownership makes the stakes unusually high. The technology may be transformative and the portfolio may still generate major gains; neither outcome eliminates the need for careful accounting and financing analysis.
What happens next depends less on an abstract verdict about whether AI is a “bubble” and more on whether capacity becomes productive, customers pay, financing stays available and returns clear the cost of capital. For SoftBank investors, the real question is whether Masayoshi Son’s strategy can compound asset value faster than its funding and execution risks compound.
Frequently asked questions
Did SoftBank lose $7.1 billion in one quarter?+
Yes. SoftBank Group reported an approximately ¥1.12 trillion, or about US$7.1 billion, net loss attributable to owners for the July–September 2026 quarter. The exchange-rate conversion is approximate and the figure is an accounting result, not cash burnt in that amount.
Did OpenAI cause SoftBank’s $7 billion loss?+
No such conclusion follows. The quarter included a major US data-centre equipment charge, financing costs and investment/other accounting effects. SoftBank’s US$64.6 billion cumulative OpenAI investment is a separate disclosure.
How much has SoftBank invested in OpenAI?+
SoftBank Group officially disclosed US$64.6 billion of cumulative investment and roughly 13% ownership after its October 1, 2026 final US$10 billion follow-on tranche. Invested capital is not the current market value of the private stake.
What was the $3.7 billion write-down?+
It related to advance equipment and power-generation capacity payments for US AI data-centre plans that were revised. Potential future equipment-purchase rebates of up to US$2.1 billion are not equivalent to a guaranteed immediate cash refund.
Did SoftBank cancel its Ohio AI data centre?+
The disclosures and reporting describe revised equipment procurement plans and charges; they do not establish that the entire Pike County Ohio project was cancelled. Further official project updates are needed.
Why did SoftBank stock fall after earnings?+
Investors reacted to a larger-than-expected net loss, equipment costs, fast-growing financing expenses and wider pressure on AI valuations. Shares dropped as much as about 10.5% intraday on November 11; that is not necessarily the closing percentage.
How much were SoftBank’s financing costs?+
Reuters reported approximately ¥462 billion in financing costs for the July–September 2026 quarter, more than double year-earlier levels. This is not the coupon on every debt security.
What is SoftBank Group’s LTV ratio?+
Its official report indicated a 15.9% loan-to-value ratio as of September 30, 2026. It is a dated indicator that may change as asset prices, loans and collateral arrangements change.
Is SoftBank the same as the Japanese telecom SoftBank Corp.?+
No. SoftBank Group Corp. (Tokyo: 9984) is the investment holding company discussed here. SoftBank Corp. is a distinct listed telecom operator with its own results and ticker.
Does the $56.5 billion funding raise mean SoftBank made that much revenue?+
No. The US$56.5 billion refers to financing raised during the quarter across loans and bonds, not sales or net profit, and some funding may refinance existing obligations.
Could an OpenAI IPO help SoftBank?+
Possibly, through price discovery and eventual liquidity, but any future listing, stake sale or realised gain is uncertain. There was no completed OpenAI IPO or automatic cash payout as of this publication date.
Is SoftBank stock a buy after its fall?+
There is no universal answer. Consider project economics, funding maturities, collateral terms, private-asset valuation assumptions and personal risk tolerance. A large price drop alone does not establish undervaluation or insolvency.
Put it into practice
Use the risk maths next to the guide.
Open TradeLuma's free position-size, risk/reward, expectancy, and drawdown tools to test the numbers behind a risk-management decision.
Open free trading calculators →Continue learning
Related guides.
CoreWeave's 50% Stock Crash: Is Nvidia's AI Cloud Partner Sitting on a Debt Time Bomb?
CoreWeave stock plunged roughly 49% in a month as some bonds yielded 15%. Explore CRWV debt, Nvidia ties, $104B backlog and November 10 earnings risks.
Nvidia's $330 Billion Intraday Meltdown: Jensen Huang Board Probe Shakes the AI Trade
Nvidia's Nov. 9, 2026 sell-off, Jensen Huang board investigation, $330B intraday swing, China AI-chip risks and the November 17 earnings catalyst explained.
Anthropic's $69.3 Billion IPO Proposal Was Withdrawn: What Changed?
Updated 11 Nov: Anthropic retracted the $69.3B draft and filed a new $70–$78 IPO range, up to $64.35B. Historical Nov 10 analysis of AI compute economics.