
AI Stocks & Markets
CoreWeave's 50% Stock Crash: Is Nvidia's AI Cloud Partner Sitting on a Debt Time Bomb?
CoreWeave stock plunged roughly 49% in a month as some bonds yielded 15%. Explore CRWV debt, Nvidia ties, $104B backlog and November 10 earnings risks.
On this page+
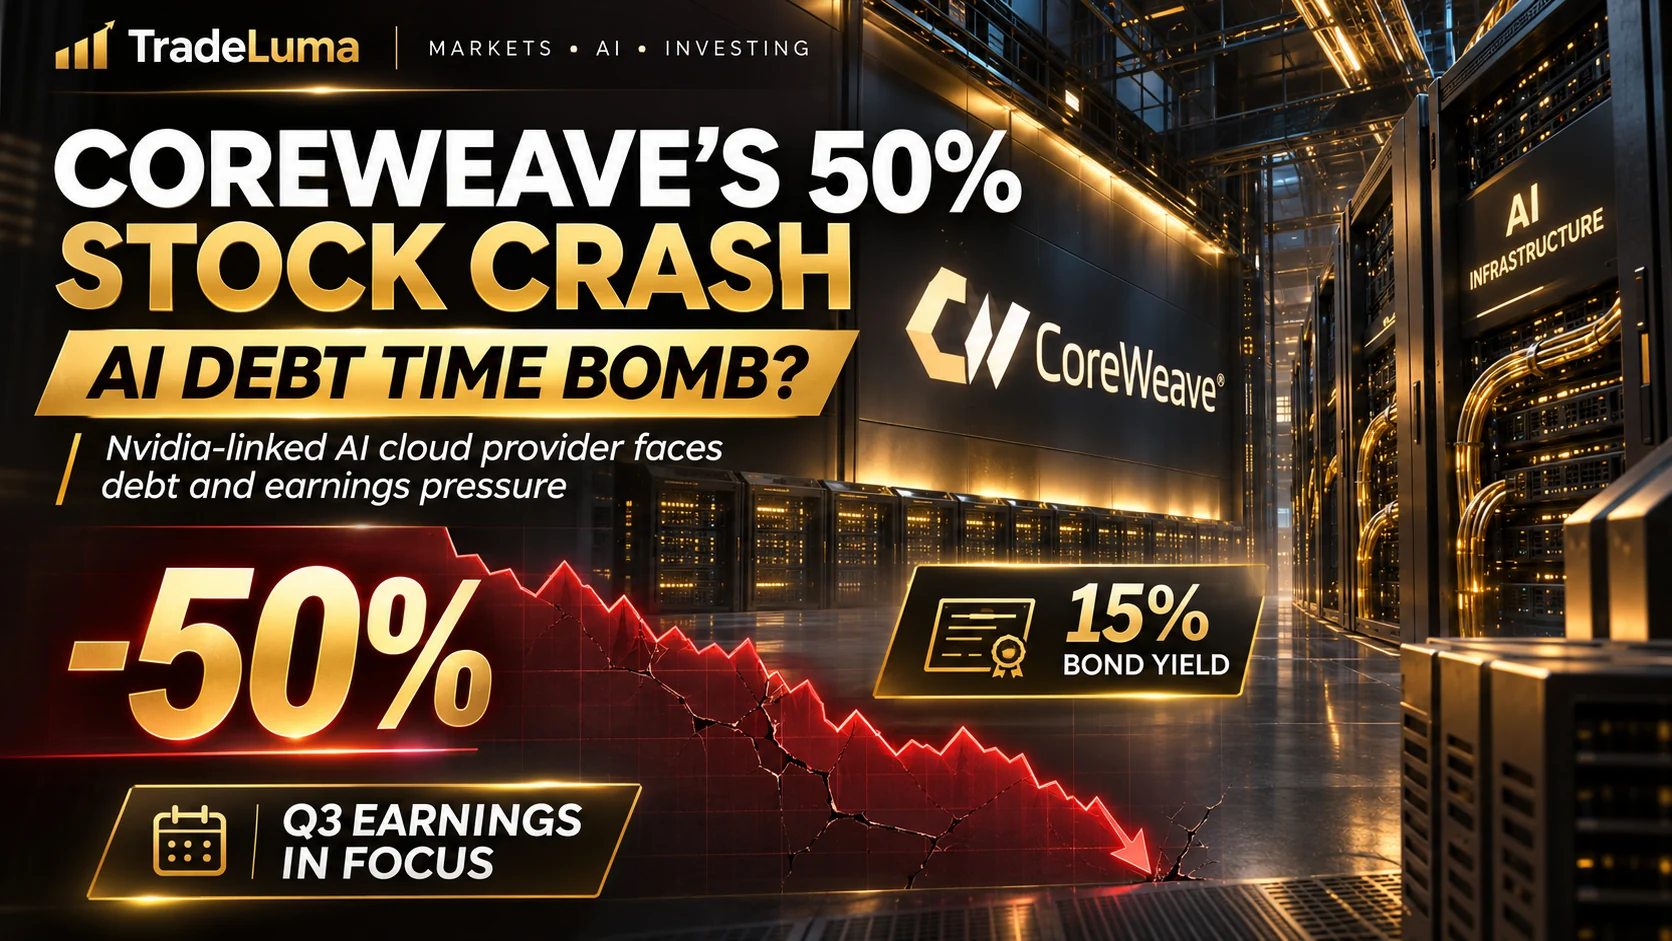
CoreWeave shares have become a stress test for the economics of the AI boom. Between the October 6 and November 6, 2026 closing prices, CRWV fell from US$91.72 to US$46.40—a decline of approximately 49.4%. It recovered to around US$49.00 on Monday, November 9, but the broader rout left investors asking whether the Nvidia-linked AI cloud operator can finance its extraordinary expansion without sacrificing shareholder value. In October, selected CoreWeave bonds traded at yields near 15%, signalling investors demanded far greater compensation for credit risk. Yet the company reported US$2.575 billion in second-quarter revenue and approximately US$104.2 billion of revenue backlog at June 30. That contrast—huge contracted demand alongside heavy financing costs—makes its third-quarter earnings call, scheduled for 5 p.m. New York time on November 10, a critical catalyst. Is this a genuine debt time bomb, a harsh re-pricing of a fast-growing business, or something in between?
Why CoreWeave’s “50% stock crash” needs a date and a denominator
CoreWeave closed at US$91.72 on October 6, 2026, and US$46.40 on November 6. The difference is US$45.32, equivalent to approximately 49.4% of the October 6 price. That is the multi-week collapse behind the dramatic headline. It should not be confused with a single-day 50% move, nor with the decline from the company’s May high, which uses an entirely different starting point.
The shares recovered to approximately US$49.00 at the November 9 close, a roughly 5.6% advance from Friday. That rebound did not erase the recent losses, but it matters for anyone comparing an article headline with a current quote. The branded chart on this article’s cover is conceptual artwork, not a tick-by-tick record of CRWV trading.
What does CoreWeave actually do—and why does AI demand matter?
CoreWeave is a specialised cloud provider, often called a neocloud. Instead of primarily selling conventional enterprise software, it builds and operates infrastructure optimised for computationally intensive AI training and inference. Customers pay to use GPU systems, networking, storage and orchestration services. CoreWeave competes for work from AI laboratories, technology companies and enterprises whose demand can fluctuate with model launches and deployment needs.
The business requires enormous capital before some of the associated revenue is recognised. Chips must be ordered, data centres powered, networked and cooled, and contractual service levels met. The opportunity is real if customers use that capacity consistently at prices above total lifetime costs. The risk is that contracted demand, construction timing, chip depreciation and borrowing costs do not line up on the same timetable.
The bond-market alarm: why yields touched 15% in October
Reuters reported that bonds CoreWeave had issued in June at a yield around 9.675% fell sharply in price, pushing market yields towards 15% in mid-October. Other CoreWeave dollar notes maturing in 2031 briefly yielded above 16% during that period. These were prices for identifiable instruments at identifiable times, rather than a single weighted-average rate charged on every loan CoreWeave has outstanding.
Bond prices move inversely to their market yields. A higher yield indicates that buyers require more expected return for duration, liquidity and credit risk. It can make future unsecured financing more expensive if the company must issue new notes, but the increase does not mechanically change the fixed coupon on an existing fixed-rate bond. The company’s borrowing agreements and future refinancing calendar therefore matter more than any headline yield taken in isolation.
Does a 15% bond yield mean CoreWeave will default?
No. A high yield signals that markets are demanding substantial risk compensation; it does not establish that the borrower has missed a payment or entered insolvency. Credit-default-swap spreads also rose sharply in October. Some analysts converted those market prices into risk-neutral default probabilities, but such outputs depend on model assumptions, recovery rates and risk premia; they are not objective forecasts of an actual probability of bankruptcy.
Investors should investigate debt maturities, collateral, covenants, liquidity, customer payment terms, access to committed facilities and future free cash flow. Trouble can emerge even with strong revenue growth if refinancings become prohibitively costly. Conversely, a company with reliable contracts, ample funding access and improving operating cash generation can survive periods of stressed secondary-market debt prices.
CoreWeave’s debt stack is not a single $50 billion bond
Reuters described CoreWeave as having approximately US$50 billion of debt during the October sell-off. That broad figure encompasses different financial structures and must be read alongside CoreWeave’s filings, because secured project or equipment loans, convertible securities, leases and unsecured notes have different priority, collateral and maturity provisions. A bond with distressed pricing cannot automatically be extrapolated to the entire borrowing stack.
Secured creditors may benefit from pledged chips, contracts or project assets, while unsecured bondholders bear a different position in the capital structure. Some financing is drawn as new capacity is delivered. For common shareholders, the critical questions are how much cash must be paid over each of the next several years, whether debt agreements restrict the business, and how much of the economics remain after interest and other claims.
The “Finance 101” problem: revenue must outgrow the cost of the GPUs
A simplified AI cloud project earns rental fees from available compute capacity while incurring hardware, facilities, electricity, staffing, maintenance, depreciation and interest costs. Long-term contracts can help finance assets, but they do not remove the possibility of cost overruns or a mismatch between customer ramp-up and loan payments. Financial leverage magnifies both the return on a successful project and the damage from a disappointing one.
Higher interest rates can bite a rapidly expanding operator twice: floating-rate or new debt becomes more expensive, and the present value of distant future profits may fall. The rate paid on existing debt, the yield of new unsecured notes and the economic cost of capital across a mixed funding structure are three separate concepts. Treating a bond’s 15% yield as a company-wide financing rate would exaggerate the immediate expense.
Q2 2026 earnings: spectacular growth, stubborn losses
CoreWeave’s last reported quarter before the scheduled November 10 results was Q2, released August 11. Revenue reached US$2.575 billion, up from US$1.212 billion in the year-earlier period—approximately 112% growth. But the company posted a GAAP operating loss of US$49 million, net interest expense of US$640 million, and a net loss of US$626 million. These metrics show why a fast-growing AI revenue line does not necessarily translate immediately into net profitability.
Adjusted EBITDA of approximately US$1.51 billion looked much stronger than GAAP net income, but EBITDA excludes interest, taxes, depreciation and other items, and the adjusted version also excludes selected costs. With a business that invests in expensive, depreciating GPUs and relies heavily on financing, those exclusions are economically significant. A good analysis considers operating profit, cash flow and debt service together rather than picking the most flattering non-GAAP number.
The Q2 balance sheet: $5.5 billion cash versus $15.6 billion liquidity
The June 30 filing reported US$5.524 billion in cash and cash equivalents, about US$15 million of marketable securities and US$10.014 billion in unused availability under existing credit facilities, producing a headline total liquidity figure of approximately US$15.553 billion. Unused borrowing capacity is not the same as money already in a bank account, and using it typically creates additional debt subject to facility conditions.
Restricted cash, working capital, construction payments and near-term maturities must be analysed separately. CoreWeave stated in its Q2 filing that it expected its available resources to meet anticipated obligations within the following year. That statement is management’s view at the time of filing, not a guarantee against changed market conditions. Investors need the Q3 update before asserting that cash or facility capacity remained unchanged into November.
Why the $104.2 billion backlog matters—and what it does not mean
CoreWeave reported approximately US$104.2 billion of revenue backlog as of June 30, 2026, up strongly from a year earlier, plus more than US$25 billion in net new customer commitments announced early in Q3 that were excluded from the June backlog. The company’s definition includes remaining performance obligations and other amounts estimated to become revenue under committed customer contracts, subject to delivery and availability requirements.
Backlog is not cash on hand, an unconditional receivable or proof of future net margins. Capacity must be built, delivered and accepted; spending occurs before some revenue is booked. The key is conversion: how much of that backlog becomes recognised, collectable revenue, at what pace, with what incremental investment, and at what contribution margin after utilisation, power, network and capital costs?
Nvidia’s investment: support, incentives and their limits
Nvidia is both an important partner and a major shareholder in CoreWeave. That connection can help the neocloud secure cutting-edge hardware, technical alignment and commercial credibility. It also creates interdependencies: strong demand for AI GPUs can be good for Nvidia’s chip sales and CoreWeave’s rental demand, while a slowdown in infrastructure spending can pressure both sides for different reasons.
A strategic stake does not mean Nvidia guarantees all CoreWeave obligations, nor does it require Nvidia to defend the CRWV share price. Investors should distinguish equity ownership, GPU supply, capacity-purchase contracts and lending arrangements. Each creates a different legal obligation, and their economic effects can diverge during a funding squeeze.
The Nvidia capacity backstop is meaningful, but not unlimited
A September 2025 securities filing described a CoreWeave–Nvidia agreement with an initial value of approximately US$6.3 billion under which Nvidia agreed to purchase certain residual unsold cloud capacity through April 2032, subject to contractual termination, delivery and availability conditions. This can reduce utilisation uncertainty for qualifying capacity and is more substantial than a loose marketing partnership.
But a capacity backstop is not a blanket promise to buy every GPU hour forever, nor a guarantee that all projects yield attractive returns. The agreement’s practical value depends on the assets made available, contract pricing, eligible capacity, counterparties’ continuing performance and evolving GPU technology. It helps the bull case while leaving material financing and execution risks intact.
Why Microsoft, OpenAI and big AI contracts can cut both ways
CoreWeave has secured contracts with major AI technology customers, including Microsoft and OpenAI. Large customers can improve visibility and financing options because lenders prefer contracted cash flows to speculative demand. Yet concentration among a small number of sophisticated buyers can create bargaining pressure, renewal risk and dependence on how the largest customers adjust their internal compute strategies.
The contract amount and the timing of its recognition are not the same as immediate customer cash receipts. Some commitments have conditions tied to power availability, equipment deliveries and service quality. A delay in one large data-centre project can affect near-term revenue, interest carry and customer relationships all at once. Investors therefore need to ask how diversified the backlog has become rather than simply celebrate its headline size.
Chip obsolescence: the quiet risk behind debt-backed GPUs
AI accelerators can remain productive for years, but their market value and rental economics may change rapidly when newer generations deliver better performance per watt or per dollar. Debt-backed infrastructure can be vulnerable if an operator assumes rental prices will stay elevated for longer than actual demand allows. A rack that was scarce at contract signing may face more competition by the time a loan matures.
That does not mean older GPUs immediately become worthless. They can run inference, smaller models or cost-sensitive workloads, and contracted clients may continue paying for capacity under agreed terms. The key accounting and financial distinction is between a depreciated asset’s book value, its resale value, and the lifetime economic return from the contracts it supports.
Power, permits and construction delays can turn growth into a cash squeeze
A modern AI data centre needs more than chips: grid connections, transformers, cooling, land, permits, construction labour and reliable electricity. Delays can leave expensive equipment waiting to earn revenue or postpone the date at which contracts begin paying. The risk has become politically sensitive as communities debate water consumption, electricity bills and infrastructure expansion.
CoreWeave disclosed approximately 3.7 gigawatts of contracted power at June 30 and around 4.2 gigawatts by its August 11 update. Contracted power is not identical to fully energised capacity or GPUs already earning customer revenue. Investors should track actual energised megawatts, commissioning dates and the ratio of revenue-generating capacity to capacity financed.
What the November 10 earnings call could change
CoreWeave scheduled its Q3 2026 results call for Tuesday, November 10 at 5:00 p.m. U.S. Eastern time—Wednesday, November 11 at 9:00 a.m. Melbourne time. This article is written before that event and does not present any Q3 result as established. In August, the company provided third-quarter revenue guidance of US$3.45–3.60 billion, net interest expense guidance of US$860–940 million and capital expenditure guidance of US$11.5–13.5 billion; those are prior guidance ranges, not reported actuals.
The market will compare realised revenue with guidance, examine whether adjusted and GAAP margins are improving, assess revised full-year capital spending and ask whether access to financing remains secure. The details of interest costs, construction timing and customer prepayments could move CRWV more than a headline revenue beat. Even strong bookings may not resolve concern if the cash conversion timetable worsens.
Five metrics investors should read before reacting to Q3 headlines
First, revenue and revenue-growth quality: were new services delivered on time and are customers paying? Second, adjusted operating income versus GAAP operating profit: are improving operating economics visible after relevant costs? Third, cash from operations, capital expenditure and free cash flow: is additional expansion funded internally or through external capital? Fourth, net interest expense and updated financing availability: is debt service becoming manageable?
Fifth, the composition and timing of backlog, including dependence on large customers and delivery conditions. Pair these financial numbers with active power, contracted megawatts, actual service launches and any covenant disclosures. One-quarter performance should also be compared with a multi-year investment schedule. The more capital-intensive the business, the more important management’s reconciliation between contracted demand and cash commitments.
How CoreWeave differs from Nebius, Oracle and hyperscalers
CoreWeave and Nebius are often grouped as neocloud providers because they have large AI infrastructure ambitions and require substantial capital to grow. Oracle also provides data-centre services but has an established enterprise software franchise. The largest hyperscalers, including Microsoft, Amazon and Alphabet, generally fund AI investment through much broader operating cash flows and have different balance-sheet flexibility.
A sell-off in one financing-dependent provider does not automatically mean every AI project is unviable. It can nevertheless raise lenders’ hurdle rates for businesses with similar customer, power or construction risk. Investors should compare debt maturity profiles, contractual minimums, cash balances, revenue concentration and operating profits—not just GPU counts or company descriptions.
The bull case: stressed credit prices, valuable capacity and a strong rebound
The optimistic interpretation is that capital markets temporarily punished CoreWeave more harshly than its underlying contracts justify. If AI compute remains scarce, CoreWeave delivers capacity on schedule, and its backlog converts into profitable service revenue, the company could increase operating scale and make its debt burden easier to support. Better liquidity disclosures, financing deals at reasonable rates or improving cash generation could encourage both bondholders and equity investors.
A sustained recovery would need evidence rather than a single strong trading day. The November 9 share rebound shows that the stock can move sharply higher, but volatility works in both directions. Buyers should distinguish valuation recovery from the operational achievements needed to justify that recovery, particularly after a period of significant dilution and large capital requirements.
The bear case: refinancing costs outrun the AI rental economics
The bearish pathway begins with delayed commissioning, lower rental pricing or unexpectedly high interest rates. These forces can impair the spread between contract revenue and total lifetime costs. If cash needs exceed available facilities, CoreWeave might need to raise equity at depressed prices, issue expensive debt, sell assets or postpone expansion. Those responses can protect liquidity but dilute shareholder claims or lower future growth.
A credit squeeze could also ripple into chip suppliers, construction partners and peer providers if fewer projects are funded. Yet the most severe outcome is not inevitable: it depends on contract enforcement, financing covenants, asset values, counterparties and management decisions. The phrase “debt time bomb” is a question about risk sensitivity, not a declaration that default or bankruptcy is imminent.
What CRWV investors and traders can do with this information
For long-term investors, build a scenario model around delivered capacity, realised rental rates, interest rates, capex, contract durations and financing needs. Test outcomes in which revenue keeps rising but the cost of funding rises faster. Separate bond and equity claims: an apparently cheap share price does not make a company’s debt equally attractive, or vice versa. Avoid relying solely on optimistic price targets or dramatic headlines.
For traders, November 10 earnings can produce sharp after-hours gaps, particularly in a volatile stock already recovering from a substantial drawdown. Stops may fill away from displayed levels; option prices may incorporate considerable expected volatility; and a strong initial reaction can reverse after guidance details emerge. The article is educational, not a recommendation to buy, sell, short or leverage CRWV.
Bottom line: the AI opportunity is real, but its financing must add up
CoreWeave’s story has two simultaneous truths. Revenue and backlog suggest substantial demand for specialised AI computing; strained bond pricing, large debt obligations and heavy capital spending show the cost of serving that demand. Between October 6 and November 6 the shares nearly halved, and individual bonds briefly yielded about 15% or more, before a share-price rebound on November 9. Those are warning signals to analyse carefully, not proof that the company has run out of money.
The November 10 results should clarify whether growth can outrun funding costs. The useful investor question is not simply whether AI is a bubble, but which companies can consistently convert expensive infrastructure into cash earnings after financing, depreciation and new investment. For CoreWeave, that distinction may define the next phase of CRWV’s market story.
Frequently asked questions
Why did CoreWeave stock fall around 50%?+
CRWV declined approximately 49.4% from the October 6, 2026 close of US$91.72 to US$46.40 on November 6. Rising credit-market stress, heavy AI capital requirements and market concerns about data-centre financing contributed. It was not a one-day 50% crash.
What was CoreWeave stock trading at before the November 10 earnings?+
The regular-session closing price on November 9, 2026 was approximately US$49.00, following US$46.40 on November 6. Prices can change, and this article is dated November 10.
Did CoreWeave bonds really yield 15%?+
Yes. Selected CoreWeave dollar bonds traded at market yields near 15% in mid-October 2026, and one issue briefly exceeded 16%. These observations do not mean all outstanding CoreWeave borrowing costs 15%.
Is CoreWeave bankrupt or in default?+
The reported bond-price decline does not itself establish bankruptcy or a missed payment. Evaluating solvency requires debt maturity, liquidity, covenant and cash-flow information. This article does not claim CoreWeave is insolvent.
How much debt does CoreWeave have?+
Reuters described approximately US$50 billion of debt in October 2026. CoreWeave has several kinds of financing, so investors should consult its detailed filings rather than assume the entire amount is one unsecured bond issue.
What was CoreWeave’s latest revenue before Q3 results?+
CoreWeave reported US$2.575 billion of revenue for Q2 2026, an increase of approximately 112% year over year. Third-quarter results were scheduled for the evening of November 10.
What does CoreWeave’s $104 billion revenue backlog mean?+
The company reported approximately US$104.2 billion of revenue backlog as of June 30, 2026, subject to delivery and service conditions, excluding more than US$25 billion in early-Q3 new commitments. It is not immediate cash on hand.
Does Nvidia guarantee CoreWeave’s debts?+
No general debt guarantee follows from Nvidia’s strategic shareholding or commercial contracts. Nvidia separately has a residual-capacity purchase agreement subject to contract terms. Investors must assess each legal obligation individually.
When is CoreWeave Q3 2026 earnings?+
The company scheduled its Q3 2026 earnings call for Tuesday, November 10 at 5 p.m. U.S. Eastern time, which is Wednesday, November 11 at 9 a.m. Melbourne AEDT.
How much did CoreWeave spend on interest in Q2 2026?+
CoreWeave reported approximately US$640 million of net interest expense in Q2 2026. This is an income-statement expense, not the same as the yield on one bond traded in the secondary market.
Could CoreWeave stock recover after earnings?+
It could recover if results improve confidence in capacity delivery, financing and long-term unit economics. It could also decline if cash needs or credit risks disappoint. Neither outcome can be inferred from the previous month’s share-price fall alone.
Is CoreWeave the same business as Nvidia, Nebius or Oracle?+
No. CoreWeave is an AI-focused cloud infrastructure provider. Nvidia primarily designs and supplies AI chips, while Nebius and Oracle have different customer mixes, financial structures and infrastructure strategies.
Put it into practice
Use the risk maths next to the guide.
Open TradeLuma's free position-size, risk/reward, expectancy, and drawdown tools to test the numbers behind a risk-management decision.
Open free trading calculators →Continue learning
Related guides.
Nvidia's $330 Billion Intraday Meltdown: Jensen Huang Board Probe Shakes the AI Trade
Nvidia's Nov. 9, 2026 sell-off, Jensen Huang board investigation, $330B intraday swing, China AI-chip risks and the November 17 earnings catalyst explained.
Anthropic's $69.3 Billion IPO Gamble: Is the AI Bubble Facing Its Biggest Test?
Anthropic's reported $69.3B IPO ambition meets $895.4B in compute commitments. Explore Claude growth, IPO risks, valuation and the AI trade.
Why Google Stock Fell After Earnings While Microsoft Rose: The AI Cash Flow Test
Google vs Microsoft October 2026 earnings explained: why Alphabet fell after hours while Microsoft gained, AI capex, Azure, Google Cloud and free cash flow.